Verizon's Comeback Story: From Laggard to Leader 🚀
For years, Verizon Communications (NYSE: VZ) was the sleepy giant of the telecom sector — reliable dividend, minimal growth, and a stock that seemed permanently stuck in neutral. That narrative has flipped in 2026.
Under CEO Dan Schulman, who took the helm in October 2025, Verizon is executing a turnaround that has caught Wall Street's attention. The stock is up more than 25% year-to-date, and the question investors are now asking is simple: is this rally just getting started, or has the easy money already been made?
📌 Key snapshot: Market cap of $201B, 5.78% dividend yield, and a Moneyball Superscore of 70/100.

The Three Pillars of Verizon's Turnaround 🏗️
1. Operational Momentum Is Real
In Q2 2026, Verizon reported 184,000 postpaid net phone additions — a stunning reversal from a net loss just one year earlier. This isn't a rounding error; it signals that Verizon is winning back subscribers it had been bleeding to T-Mobile and AT&T.
2. The Frontier Deal Is Paying Off
Verizon's acquisition of Frontier Communications has expanded its fiber broadband connections by over 43% year-over-year. Fiber is the high-margin, sticky product that telecom investors have been waiting for, and Verizon now has scale.
3. Cost Discipline Under Schulman
Management is targeting $5 billion in cost cuts in 2026 alone. Combined with expanding EBITDA and margins, this is the kind of operational leverage that drives multiple expansion.
Competitive Context
T-Mobile and AT&T are both performing solidly — but neither has Verizon's current momentum. In a sector where differentiation is rare, Verizon is the one with a story to tell. 🎯
The bull and bear cases for Verizon are both compelling — here's how the debate is playing out on the Street.

Valuation & Technical Picture 📊
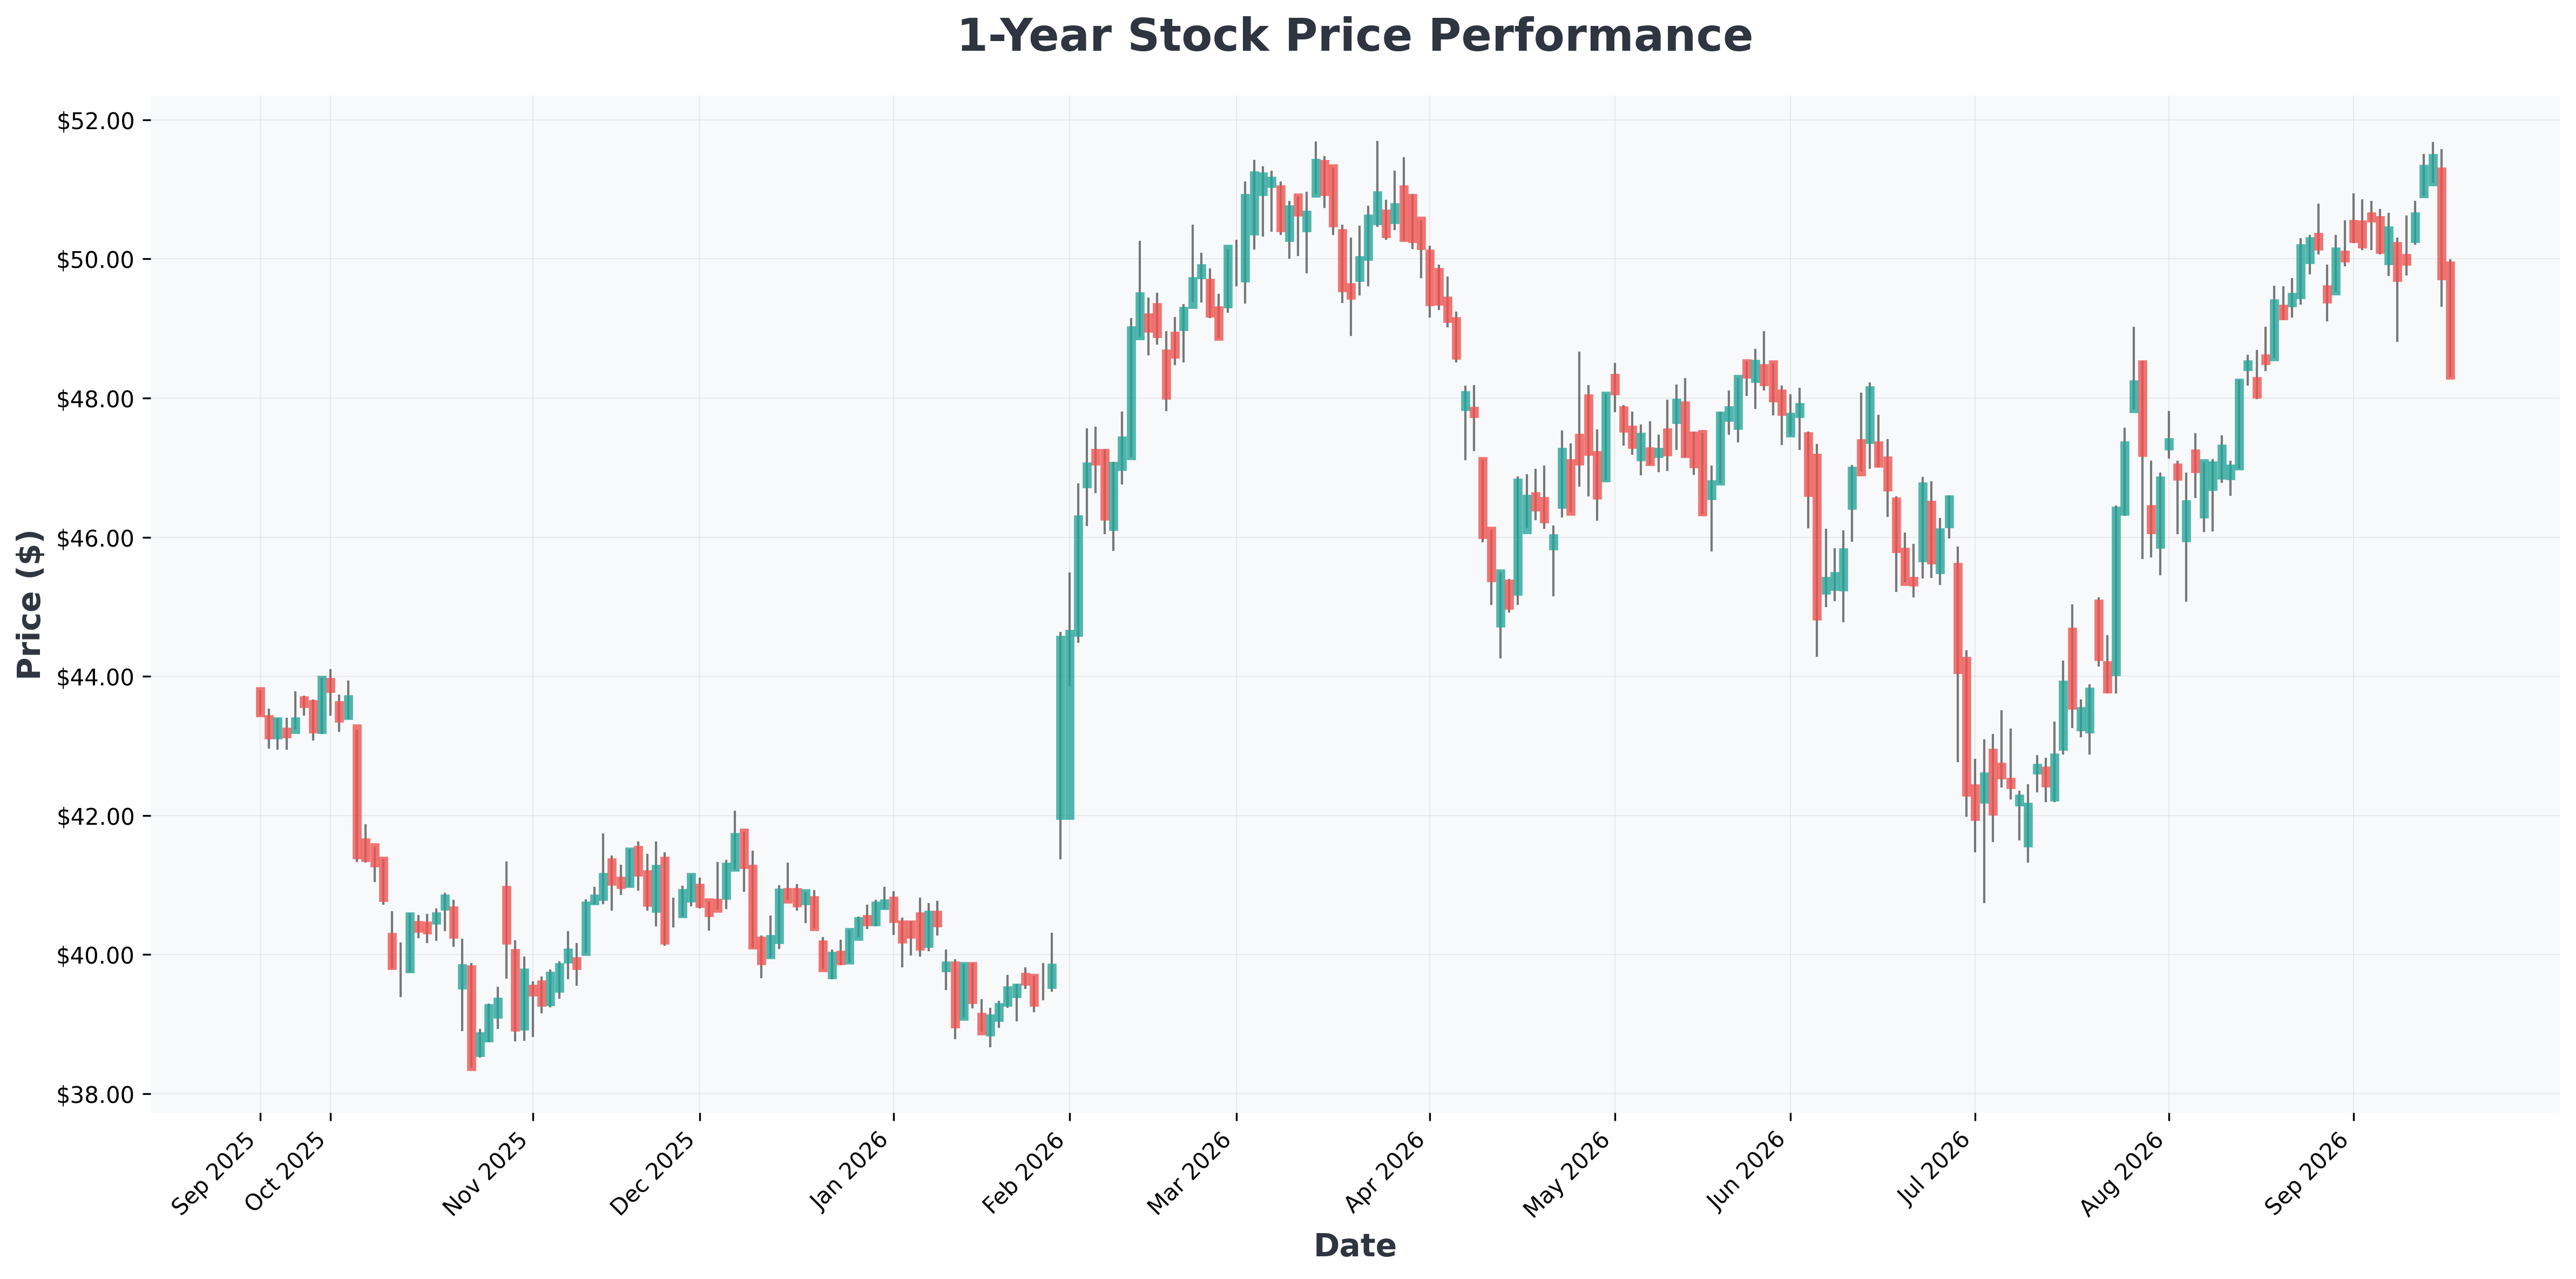
At $48.09, Verizon trades at a reasonable multiple relative to its improved growth trajectory. The 52-week range of $38.39–$51.68 shows the stock is pressing against resistance near $51–52, a level that has capped rallies in prior cycles. A clean break above that zone would open the door to the mid-$50s.
| Metric | Value |
|---|---|
| Current Price | $48.09 |
| 52-Week Range | $38.39 – $51.68 |
| Market Cap | $201B |
| Dividend Yield | 5.78% |
| Gross Margin | 45.71% |
| Avg Volume | 25.8M |
| YTD Performance | +25% |
🔍 Backtesting note: Historically, when VZ has broken above its prior 52-week high on above-average volume, it has tended to consolidate for 4–6 weeks before continuing higher. Watch the $51.68 level closely — it's the line in the sand.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| T (AT&T) | $25 | 8.38 | 1.58 | 18.34% | 24.79% | 2.30% |
| TMUS (T-Mobile) | $168 | 17.61 | 3.21 | 17.99% | 25.22% | 7.90% |
| TpC (Tutor) | $85 | 36.64 | 3.68 | 13.74% | 7.22% | 19.20% |
| VZ (Verizon) | $48 | 12.52 | 1.92 | 15.84% | 23.00% | -0.70% |

Scenario Analysis: Where Does VZ Go From Here? 🧭
🐂 Bull Case (Best Scenario)
- Schulman's cost cuts deliver ahead of schedule, pushing EBITDA margins above 40%.
- Frontier integration drives fiber ARPU higher, and Verizon guides up on 2027 subscriber growth.
- Stock breaks $52 resistance and re-rates toward $58–60 as dividend investors pile back in.
🐻 Bear Case (Worst Scenario)
- T-Mobile and AT&T respond with aggressive promotions, slowing Verizon's subscriber momentum.
- Frontier integration costs balloon beyond the $5B savings target.
- Rising rates pressure the dividend trade, and VZ retests the $42–44 support zone.
Bottom Line
The turnaround is real, but the easy 25% has already been captured. For income investors, the 5.78% yield remains attractive. For growth-oriented investors, the next leg depends on whether Schulman can sustain the subscriber wins into 2027. This is a stock worth watching closely — but not one to chase blindly at the highs. ⚠️
All investing involves risk, including potential loss of principal. Do your own due diligence.
