The AI semiconductor boom is red-hot, and investors are understandably fixated on the flashy chip designers like Nvidia and AMD. 📌 However, the real 'picks and shovels' play might be the giant behind them: Taiwan Semiconductor Manufacturing (TSMC). This article breaks down why TSM is arguably the most strategically positioned company to benefit from the explosive growth in AI computing, offering a unique blend of scale, technological leadership, and financial strength.

The Unseen Powerhouse: Why TSMC is the Bedrock of AI 🏭
Nvidia and AMD design cutting-edge GPUs and CPUs, but they don't manufacture them. They rely on TSMC's advanced fabrication plants to bring their designs to life. This makes TSMC the indispensable partner in the AI ecosystem.
- A Diversified Empire: Unlike Nvidia, which is heavily reliant on AI data center demand, TSMC's client roster reads like a who's who of tech: Apple, Qualcomm, Broadcom, Amazon, Microsoft, and Alphabet. This diversification not only captures AI data center growth but also the rising demand for AI-capable PCs and smartphones, providing a more stable and comprehensive revenue stream.
- Technological Monopoly: TSMC's lead in advanced process nodes (like 3nm and the upcoming 2nm) is staggering. With a ~73% share of the global foundry market, they hold immense pricing power. This allows them to plan a significant 25% price increase for additional AI chip capacity next year, a clear sign of their market dominance.
The Growth Engine is Accelerating 🚀
TSMC's financials are reflecting this strategic advantage. Revenue for the first seven months of 2026 is up 37% year-over-year, with July alone showing a 45% jump. This momentum suggests the company will comfortably beat its already-upgraded full-year guidance of 40% growth.
The market's outlook on TSMC is overwhelmingly positive, but a closer look reveals a nuanced debate. Here’s a look at both sides of the coin.
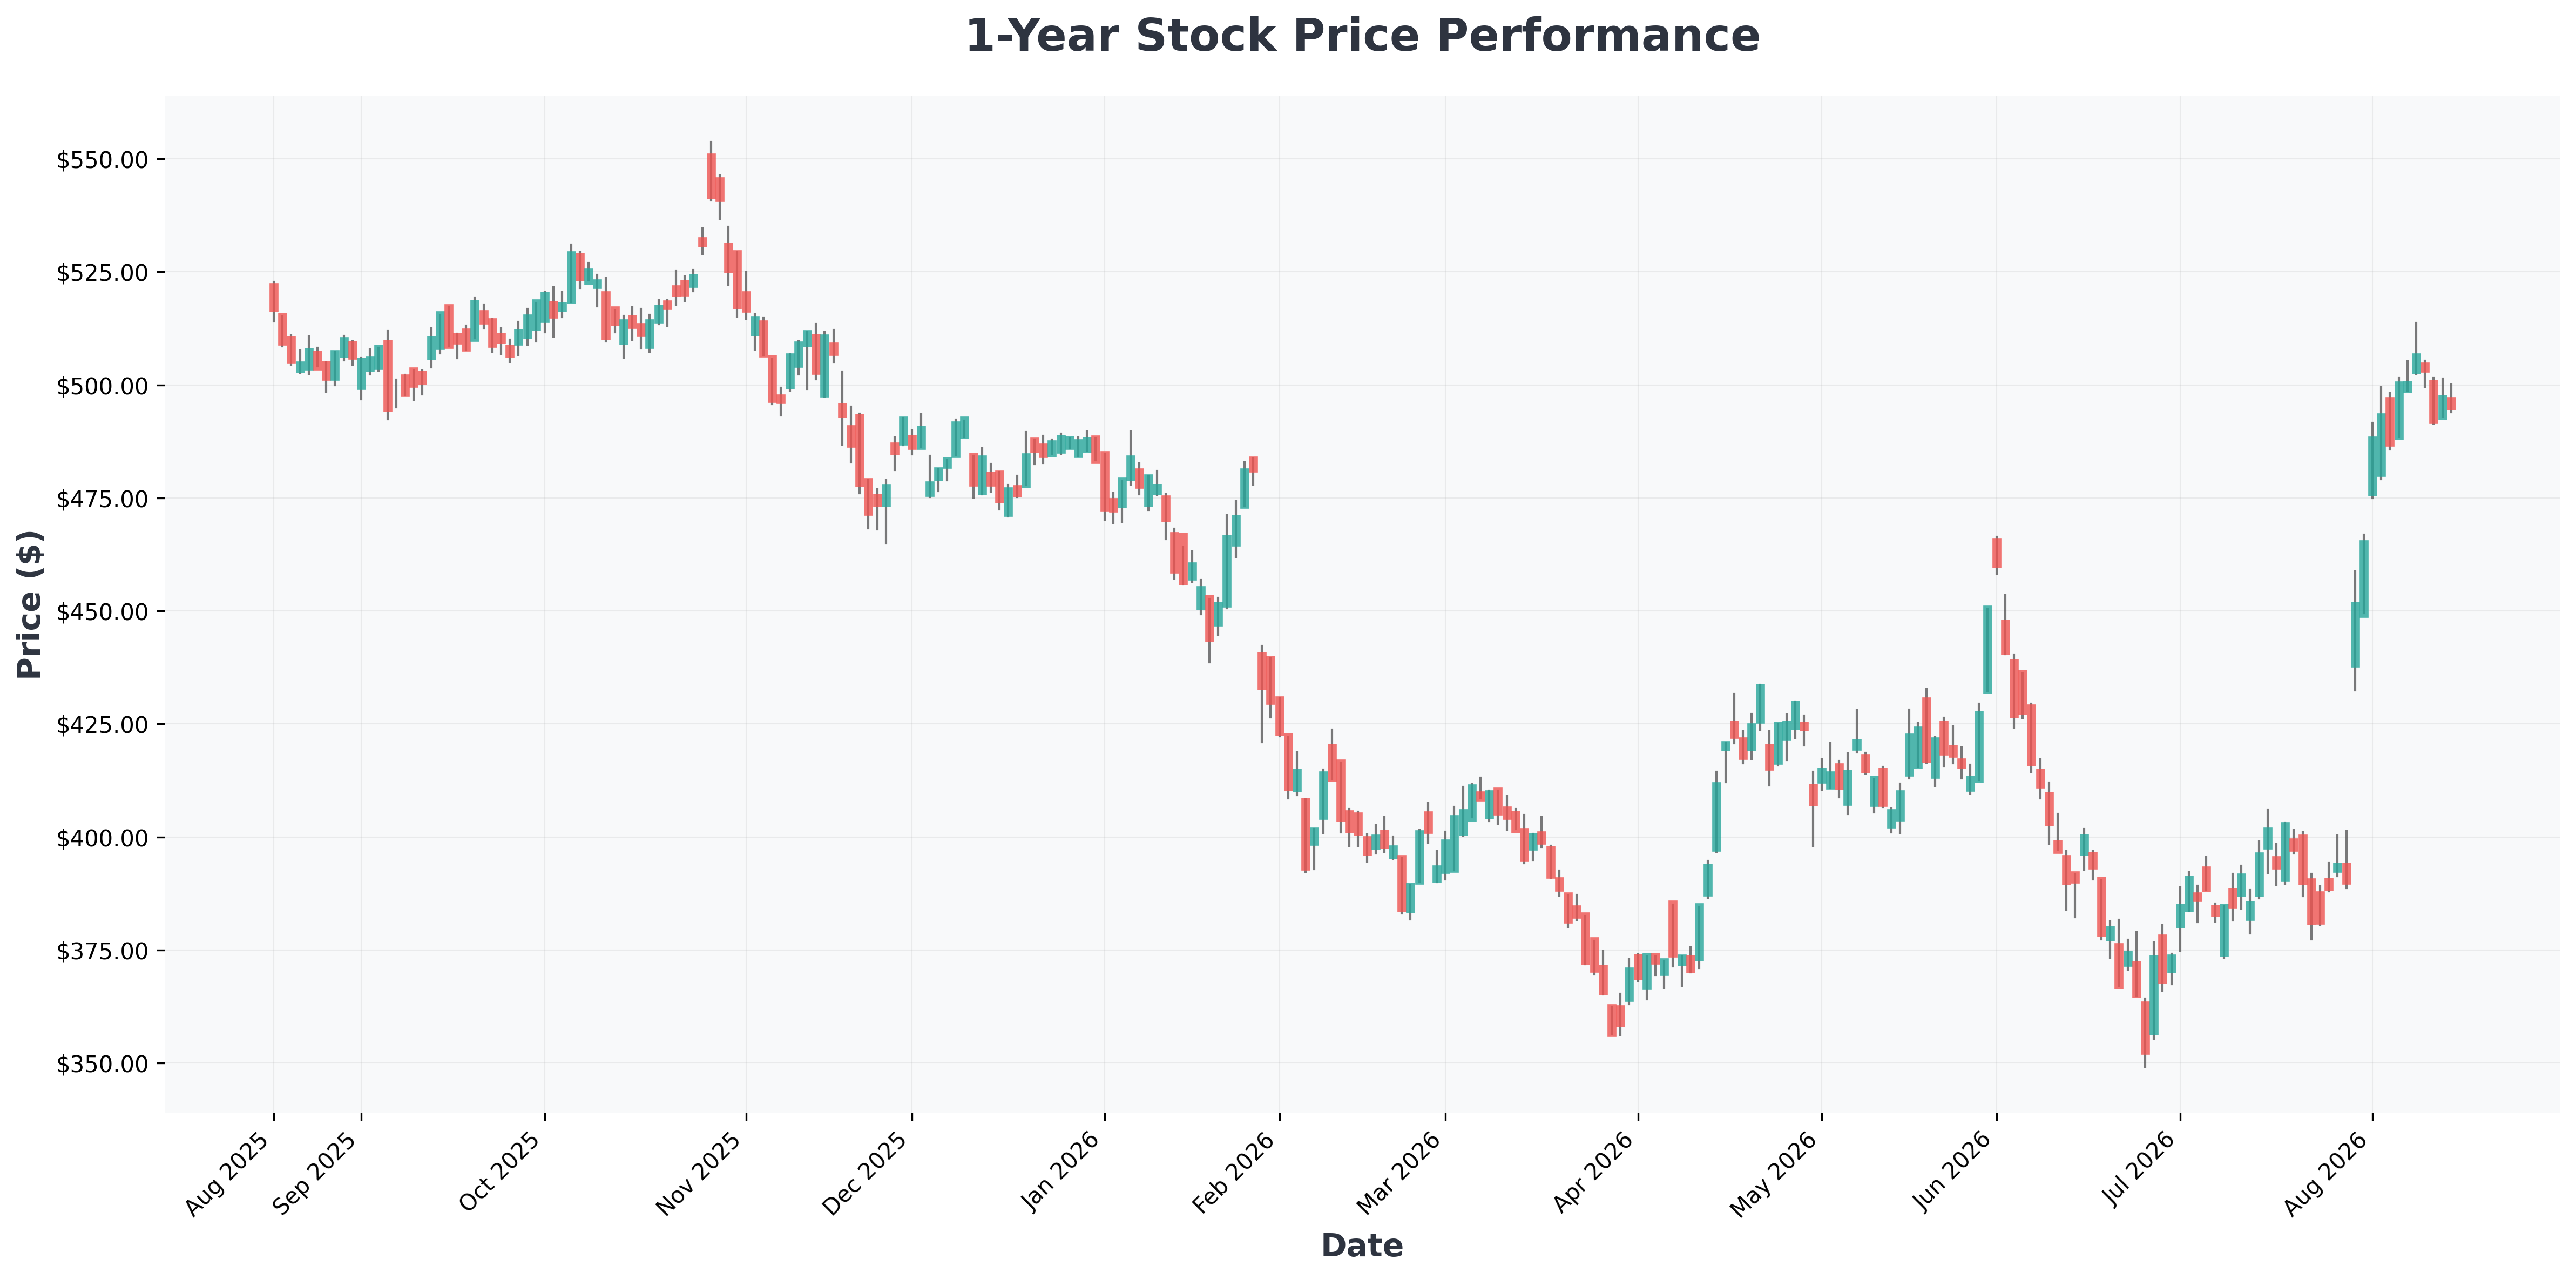
The Bull vs. Bear Debate: Is the Growth Priced In? 🤔
The consensus is bullish on TSMC, but it's worth examining both sides of the trade to understand the full risk/reward profile.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| AAPL (Apple) | $306 | 35.08 | 41.57 | 148.75% | 32.62% | 16.40% |
| AMD (Advanced) | $514 | 131.56 | 12.49 | 10.20% | 17.25% | 50.10% |
| AMZN (Amazon.com,) | $263 | 21.15 | 5.13 | 30.56% | 13.69% | 19.60% |
| AVGO (Broadcom) | $393 | 65.39 | 21.32 | 37.28% | 48.99% | 47.90% |
| GOOG (Alphabet) | $344 | 17.24 | 6.75 | 48.68% | 34.03% | 24.20% |
| GOOGL (Alphabet) | $346 | 17.36 | 6.80 | 48.68% | 34.03% | 24.20% |
| MSFT (Microsoft) | $495 | 27.63 | 8.32 | 34.04% | 45.11% | 17.70% |
| NVDA (NVIDIA) | $225 | 34.48 | 27.90 | 114.29% | 65.60% | 85.20% |
| QCOM (QUALCOMM) | $166 | 18.95 | 6.34 | 33.75% | 18.53% | -4.00% |
| TSM (Taiwan) | $426 | 32.15 | 88.92 | 39.97% | 60.34% | 36.00% |

Scenario Analysis & Conclusion: The $848 Question 💰
Bullish Scenario:
- TSMC's 2nm process node sees massive adoption from AMD, Nvidia, Apple, and others.
- The company successfully executes its price increases, expanding already impressive gross margins.
- Earnings per share (EPS) reaches $28.26 by 2028.
- If the market assigns a premium forward P/E of 30x (which is plausible given its growth and dominance), the stock price could reach $848, nearly double its current level.
Bearish Scenario:
- A severe global economic downturn leads to a cutback in consumer electronics and enterprise IT spending.
- Geopolitical tensions surrounding Taiwan escalate, creating a significant risk premium on the stock.
- Competition from Samsung or Intel unexpectedly narrows the technological gap, pressuring TSMC's pricing power.
Our Take: While the bear case is valid, TSMC's technological lead and strategic importance make it a core holding for any long-term tech investor. The stock is not cheap, but its growth trajectory and market position justify its premium valuation. Unlike the higher-flying Nvidia, TSMC offers a more balanced risk-reward and remains a powerful way to play the AI boom.
Disclaimer: This analysis is for informational purposes only and does not constitute financial advice. Investing involves risk, including the potential loss of principal.
