The Billionaire's Playbook: Beyond the AI Hype 🧠📌
Stanley Druckenmiller, one of the most successful trend-following investors of our time, has been making headlines for his early moves on Nvidia. But a closer look at his latest 13F filing reveals a far more interesting narrative. His top holding isn't an AI chipmaker or a big tech giant—it's Natera (NASDAQ: NTRA), a genetic testing company that has quietly become a portfolio heavyweight.
With nearly 20% of his U.S. equity portfolio parked in NTRA, Druckenmiller is signaling a major conviction in the future of precision medicine. But he hasn't abandoned the AI trade entirely. His stakes in Amazon (AMZN) and Alphabet (GOOGL) show a calculated shift from 'picks and shovels' to the 'application and infrastructure' layer of the AI boom. 📊

The AI Infrastructure Duo: Amazon & Alphabet 🚀
Druckenmiller's approach to AI is evolving. While he famously exited Nvidia (NVDA) in early 2024 due to valuation concerns, he's kept his foot in the door via the companies that use AI chips to build massive cloud businesses.
- Amazon (AMZN): The AWS growth engine is firing on all cylinders. With a 37% YoY revenue surge to $42.2 billion last quarter, AWS is seeing an unprecedented backlog of AI cloud services demand. CEO Andy Jassy's vision of a potential $1 trillion annual revenue run-rate highlights the massive TAM for cloud infrastructure. This isn't just about e-commerce; it's a pure-play on the digitization of everything. 📈
- Alphabet (GOOGL): This is a more nuanced bet. Google Cloud is growing at a blistering 82% YoY, albeit from a smaller base. The success of Gemini, now with nearly 950 million monthly users, provides a direct consumer and enterprise AI moat. However, the pressure on Google Search from AI-powered competitors is a real risk. Druckenmiller's stake here is a bet that Alphabet can navigate this transition. ⚖️
These two megacaps provide the stability and scale that anchor the portfolio's AI thesis, but they are not the main event. They are the 'safe' AI plays.

The Crown Jewel: Natera (NTRA) & The Genomics Disruption 🧬💎
Here is where the real money is. Natera is a disruptor in the genetic testing space, focusing on oncology, women's health, and organ transplantation. It's a classic Druckenmiller play: identifying a high-growth disruptor before the broader market catches on.
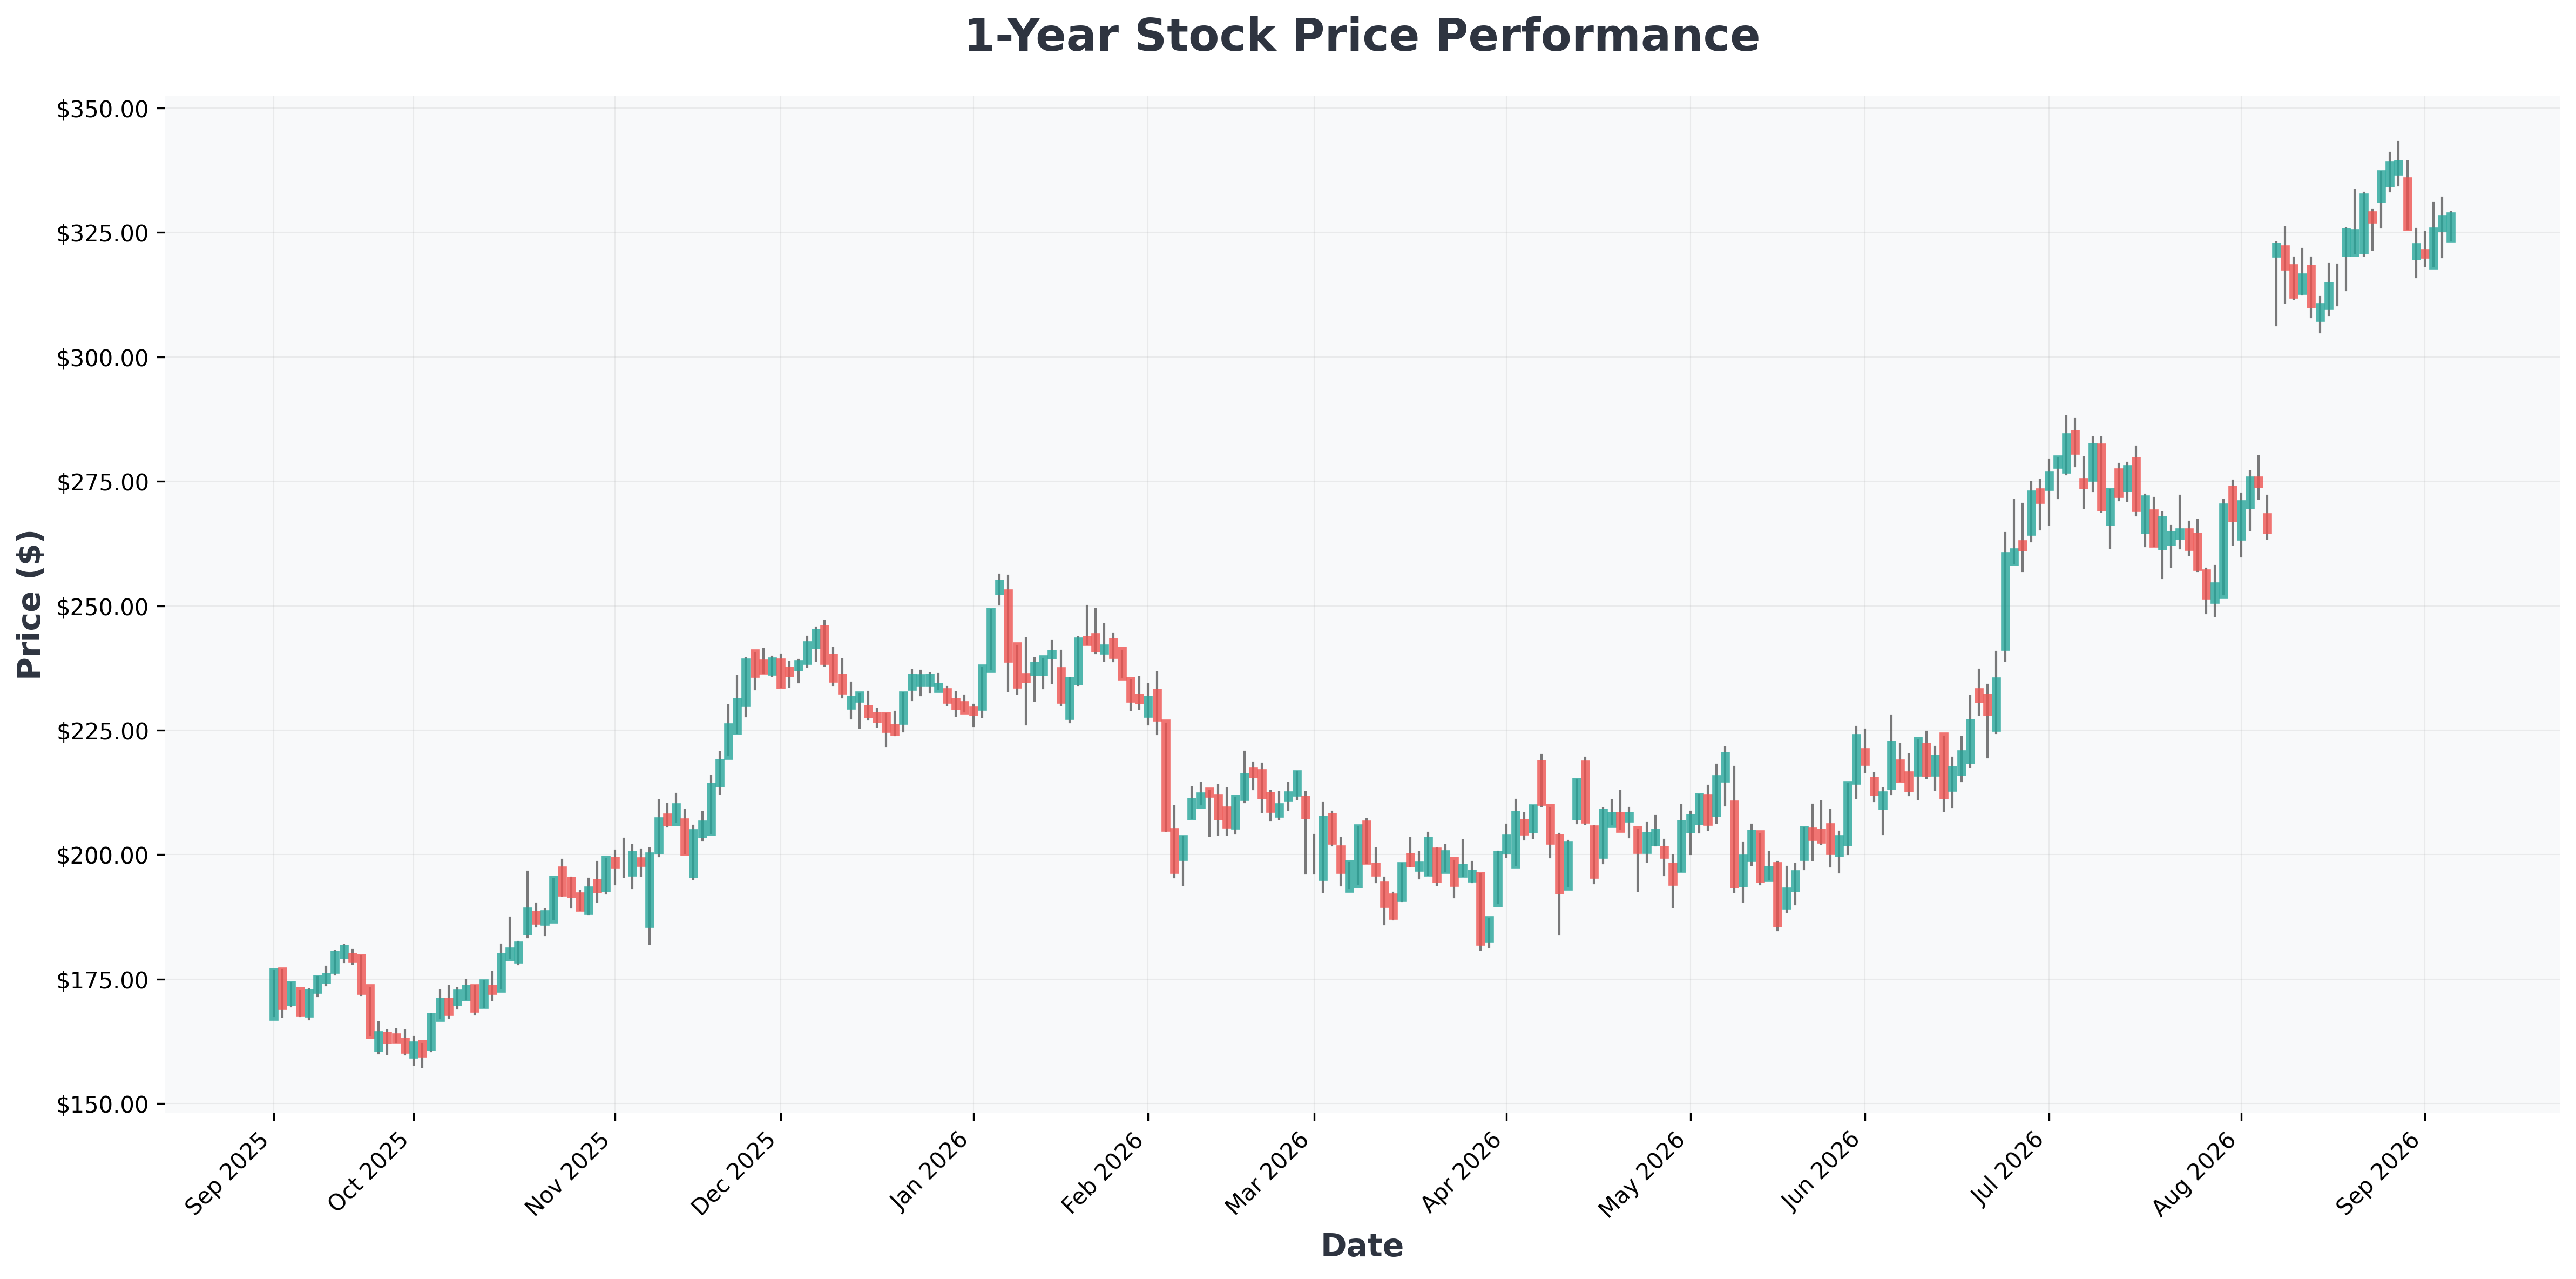
- Financial Momentum: Revenue grew 38% YoY to $753 million, leading to raised full-year guidance. The market has responded, with the stock up over 300% in the last year alone. Druckenmiller's cost basis was between $35-$50; at $324, this is a massive winner. 🤑
- The 'Why': Natera isn't just a diagnostics company; it's a data company. Each test builds a proprietary database that improves the accuracy and utility of future tests, creating a powerful competitive moat. As liquid biopsy and early cancer detection become standard of care, Natera is positioned to be a dominant player.
Technical Perspective: From a chart analysis standpoint, NTRA has broken out of a multi-month consolidation pattern. The stock is now trading near its 52-week high of $343. A pullback to the $300 psychological level could offer a potential entry point for trend-followers, with the 50-day moving average acting as a dynamic support level.
The market is clearly divided on Natera's valuation. Is it a high-growth disruptor with a clear runway, or is the market getting ahead of itself? Let's hear from both sides of the trade.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| NTRA (Natera,) | $324 | 0.00 | 25.56 | -12.54% | -10.29% | 37.70% |
| AMZN (Amazon.com,) | $257 | 20.67 | 5.02 | 30.56% | 13.69% | 19.60% |
| GOOGL (Alphabet) | $338 | 16.97 | 6.65 | 48.68% | 34.03% | 24.20% |
| TSM (Taiwan) | $439 | 32.59 | 89.84 | 39.97% | 60.34% | 36.00% |
| NVDA (NVIDIA) | $226 | 28.57 | 23.80 | 117.21% | 66.24% | 105.90% |
| GOOG (Alphabet) | $335 | 16.84 | 6.59 | 48.68% | 34.03% | 24.20% |

The Nvidia Exit & The TSMC Pivot 🎯
Druckenmiller's sale of Nvidia was a rare misstep, which he has openly admitted. Selling at a split-adjusted $80-$90 when it now trades at $230 was a lesson in letting winners run.
However, his pivot to Taiwan Semiconductor Manufacturing (TSM) is a masterstroke. Instead of buying the chip designer at a premium valuation, he's buying the monopoly manufacturer at a more reasonable price. TSM is the essential bottleneck for the entire AI revolution, making it a less risky, yet equally powerful, way to play the trend. 🔄
Scenario Analysis: The Path Forward 🧭
| Scenario | Probability | Impact on Natera (NTRA) | Impact on AMZN & GOOGL |
|---|---|---|---|
| Bull Case 🐂 | 35% | Clinical guidelines adopt Natera's tests universally. Revenue growth accelerates to 50%+. Stock could re-rate to $400+. | AWS & Google Cloud continue to see AI demand outpace supply, pushing revenues to new highs. |
| Base Case ⚖️ | 45% | Natera continues its 30-40% growth trajectory, gradually expanding market share. Stock consolidates between $300-$350 before next leg up. | Steady growth, with cloud segments growing 30%+. Stocks move higher in line with earnings. |
| Bear Case 🐻 | 20% | Increased competition in genetic testing leads to price wars. A data privacy scandal or regulatory setback hits the stock. A drop to $250 is possible. | An AI spending 'pause' or macroeconomic recession leads to cloud budget cuts. Stocks could correct 20-30%. |
Conclusion: Druckenmiller's portfolio is a masterclass in balancing disruptive growth with core stability. Natera is the high-octane, high-reward bet, while Amazon and Alphabet provide the ballast. The key takeaway for investors is to look beyond the obvious AI names and find the 'picks and shovels' of the next technological wave—in this case, genomics. 💡
