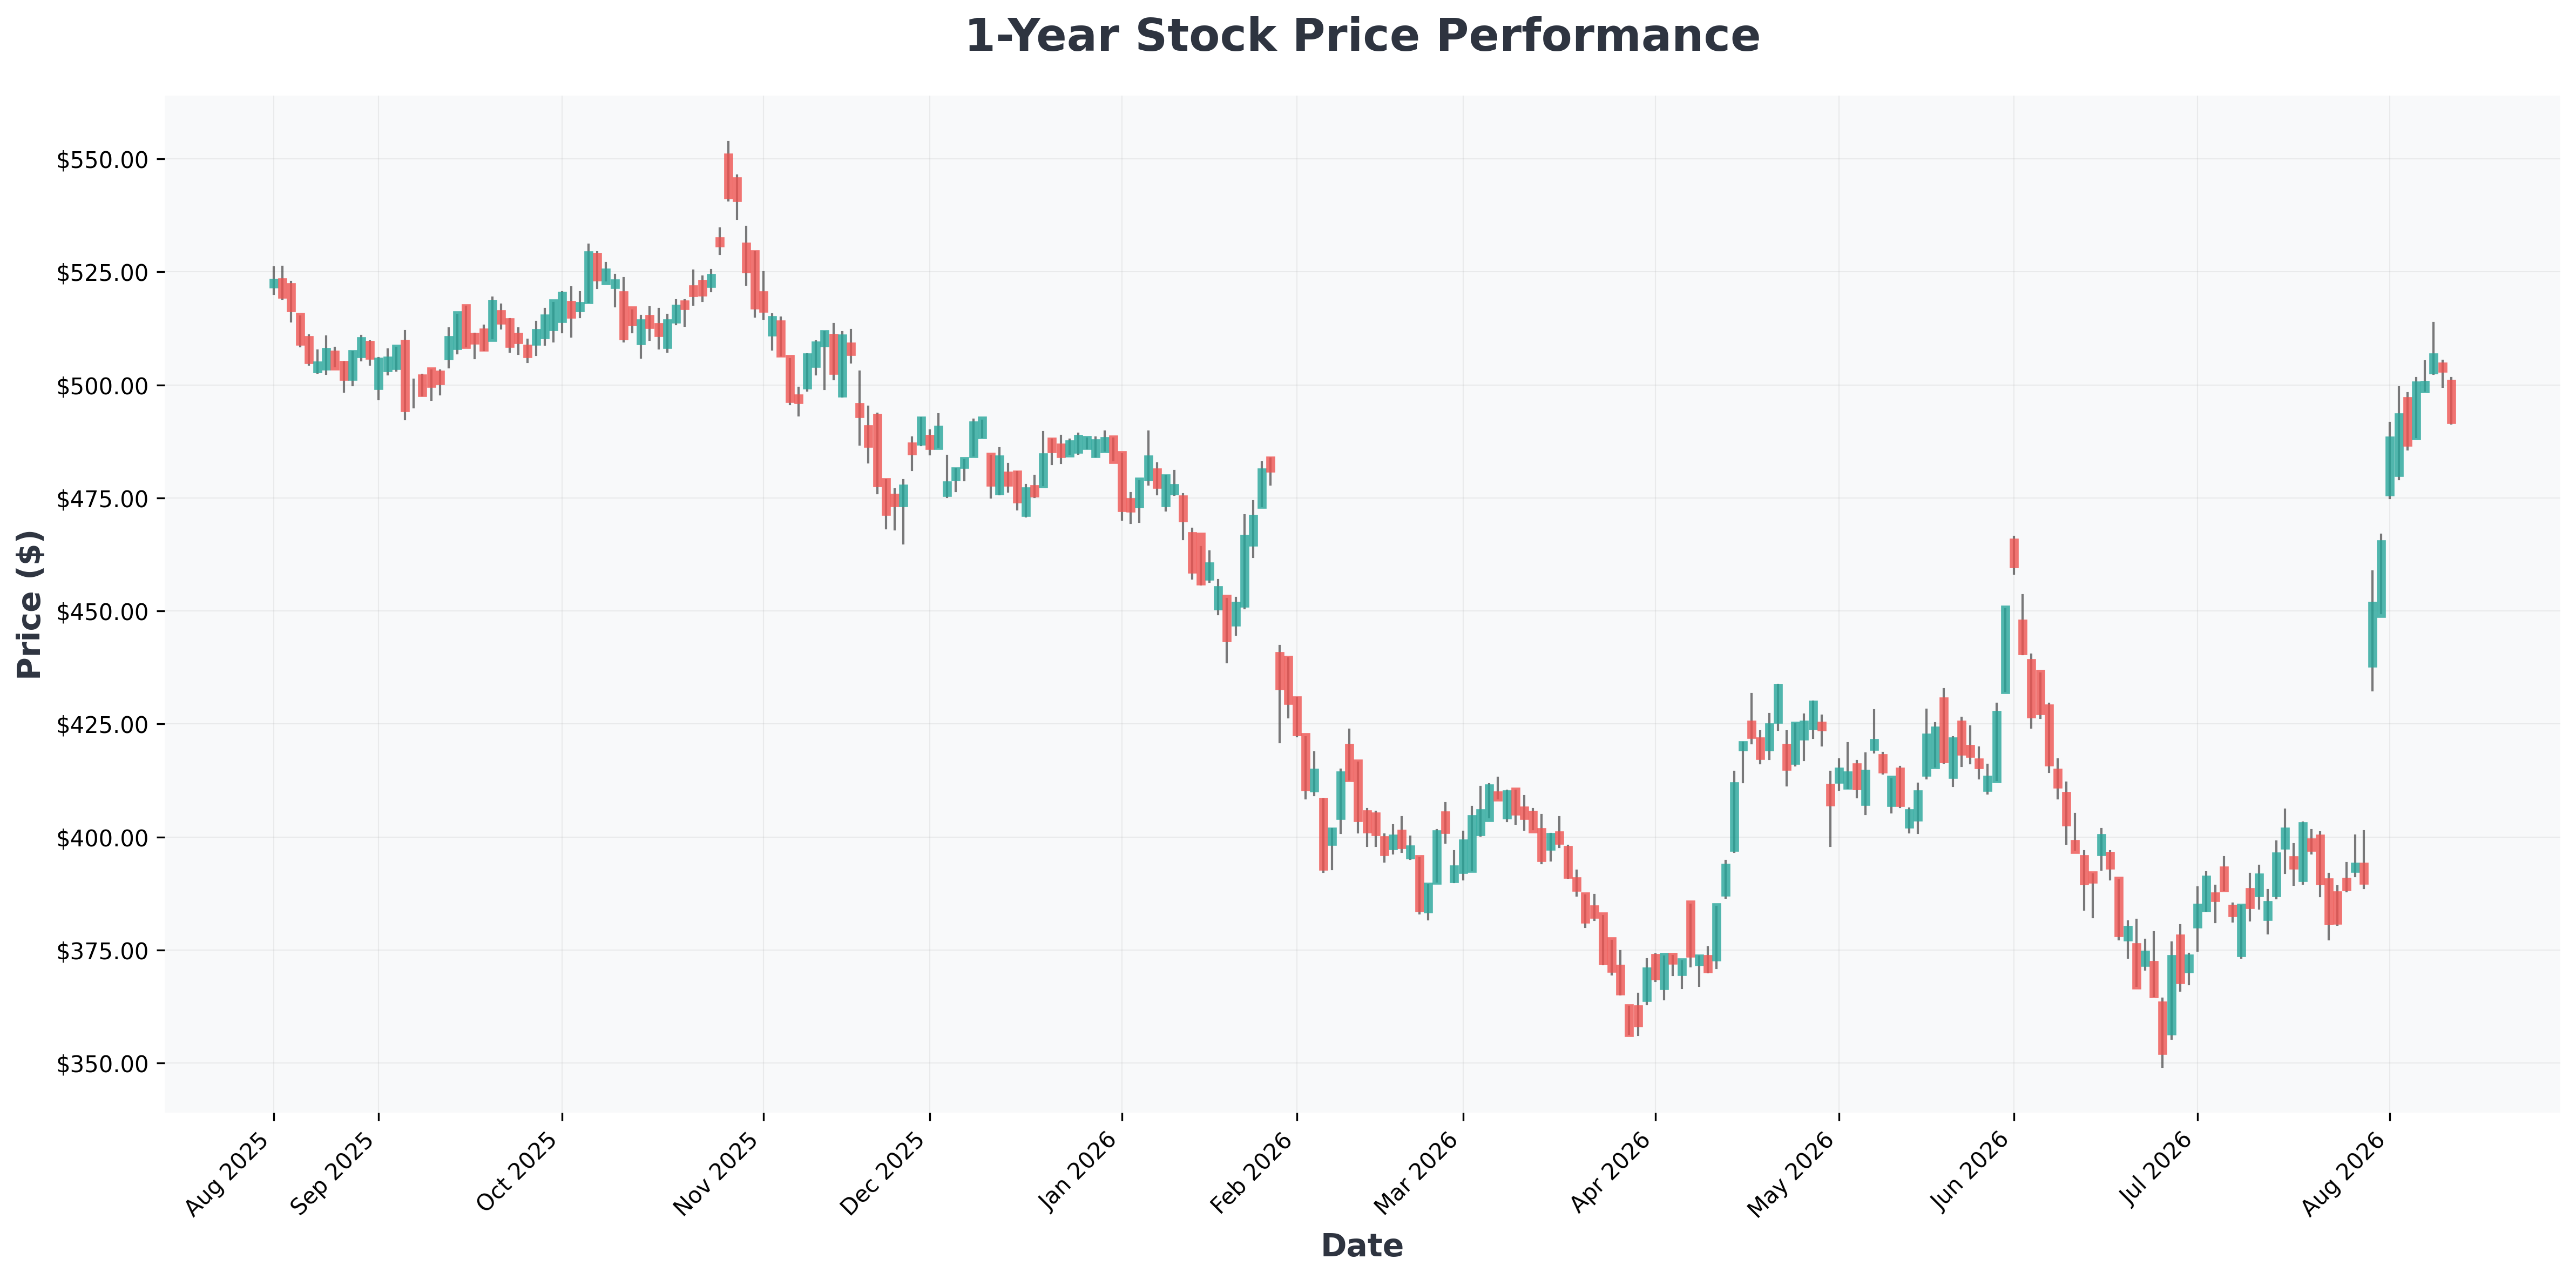
Nvidia (NASDAQ: NVDA) has been the undisputed king of the AI boom, with shares surging over 1,390% since January 2023. Yet, despite this massive run, Wall Street continues to believe the stock is undervalued. The median price target among 65 analysts sits at $300 per share, implying a 37% upside from current levels around $218.
What's driving this optimism? Simply put, Wall Street keeps underestimating how much tech giants will spend on AI infrastructure. And just recently, analysts revised their earnings estimates for Nvidia once again — this time expecting 44% annual growth over the next three years, up from the 33% estimate back in March. 🚨

Why Nvidia's Moat Is Wider Than You Think
Nvidia isn't just a GPU company anymore. It's a full-stack accelerated computing powerhouse, developing CPUs, networking equipment, and a robust software ecosystem that competitors simply can't match. This integrated approach allows Nvidia to optimize performance and power efficiency in ways that custom chips (ASICs) can't replicate.
While some investors worry that application-specific integrated circuits will eventually displace Nvidia, J.P. Morgan's global market strategist Meera Pandit dismisses those fears: "Only Nvidia chips can handle any AI workload. Custom hardware is a safe and efficient bet for known workloads like inference, but there's an obsolescence risk as AI evolves."
Nvidia has also quietly become the largest networking company in the world and is on track to become the largest CPU supplier by the end of this year. This diversification makes the bull case even stronger. 📊
This issue is dividing Wall Street. Let's look at both sides of the trade:

The Real Catalyst: Hyperscaler Capex Keeps Exploding
The most compelling reason to own Nvidia comes down to one number: hyperscaler capital expenditures (capex). Currently, 26% of all hyperscaler capex flows directly into Nvidia's revenue, according to J.P. Morgan research.
Goldman Sachs highlights a consistent pattern of underestimation:
| Year | Consensus Estimate (Start of Year) | Actual Growth |
|---|---|---|
| 2024 | ~20% | Exceeded 50% |
| 2025 | ~20% | Exceeded 50% |
| 2026 | ~30% (June) | Projected ~90% ($733B) |
| 2027 | ~28% ($939B) | TBD |
If history is any guide, analysts are likely underestimating 2027 spending too. The consensus expects 28% growth next year, but that would be a dramatic slowdown from the 56% growth in 2024, 73% in 2025, and the projected 90% in 2026. This pattern suggests Nvidia's earnings estimates could be revised even higher in the coming months. 📈
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| META (Meta) | $595 | 22.39 | 5.80 | 29.85% | 34.83% | 28.00% |
| MSFT (Microsoft) | $497 | 27.65 | 8.34 | 34.04% | 45.11% | 17.70% |
| AMZN (Amazon.com,) | $265 | 21.33 | 5.18 | 30.56% | 13.69% | 19.60% |
| GOOG (Alphabet) | $344 | 17.26 | 6.76 | 48.68% | 34.03% | 24.20% |
| NVDA (NVIDIA) | $225 | 34.56 | 27.92 | 114.29% | 65.60% | 85.20% |
| GOOGL (Alphabet) | $346 | 17.38 | 6.81 | 48.68% | 34.03% | 24.20% |
| ORCL (Oracle) | $156 | 26.84 | 11.98 | 53.38% | 36.20% | 20.60% |

Scenario Analysis & Conclusion
Bull Case (Best Scenario):
- Hyperscaler capex grows 50%+ again in 2027, beating estimates
- Nvidia maintains 90%+ GPU market share
- Earnings grow 50%+ annually, pushing the stock toward $400+ by 2028
Base Case (Most Likely):
- Capex growth moderates to ~30%, but still beats expectations
- Nvidia earnings grow 40-45% annually
- Stock reaches the $300 median target within 12-18 months
Bear Case (Worst Scenario):
- AI spending bubble bursts, capex growth slows sharply
- ASICs gain significant market share by 2027
- Nvidia stock could correct 30-40% to $130-$150 levels
While the bear case exists, the current data strongly supports the bull thesis. With consensus estimates still lagging reality, Nvidia remains a compelling long-term investment. As always, investors should size positions appropriately and consider dollar-cost averaging to manage volatility. 🎯
