The Magnificent Seven Just Got a New Discount Label 📌
The Magnificent Seven — Apple, Amazon, Alphabet, Meta Platforms, Microsoft, Nvidia, and Tesla — have been the engine behind the S&P 500's multi-year rally. Each dominates its niche, and most are directly tied to the artificial intelligence boom.
Conventional wisdom says these names should be expensive after years of outsized gains. But that assumption breaks down when you look under the hood. Earnings have grown even faster than share prices, and one name — Nvidia (NASDAQ: NVDA) — now screens as the cheapest of the entire group.
At roughly 23x forward earnings, Nvidia is trading below Meta, a stock long considered the value play among the Mag Seven. For growth investors hunting a long-term AI winner, this is the setup worth paying attention to. 🚨

Why Nvidia's Growth Engine Isn't Slowing Down
Nvidia's dominance rests on its graphics processing units (GPUs) — the chips that power AI model training and inference. That leadership has translated into staggering financials: revenue and profit have grown in double and triple digits quarter after quarter, recently hitting $96 billion and $59 billion respectively.
But the story is evolving. As AI moves from chatbots to agentic AI — systems that execute multi-step tasks and solve real-world problems — the demand profile is shifting. Nvidia is positioning itself at the center of that transition by entering the stand-alone CPU market, a segment the company estimates is worth $200 billion.
Nvidia expects $20 billion in CPU revenue this year alone as it rolls out its first chips. That's a second growth curve stacked on top of the GPU juggernaut — and it's exactly the kind of optionality that keeps valuations elevated over time.
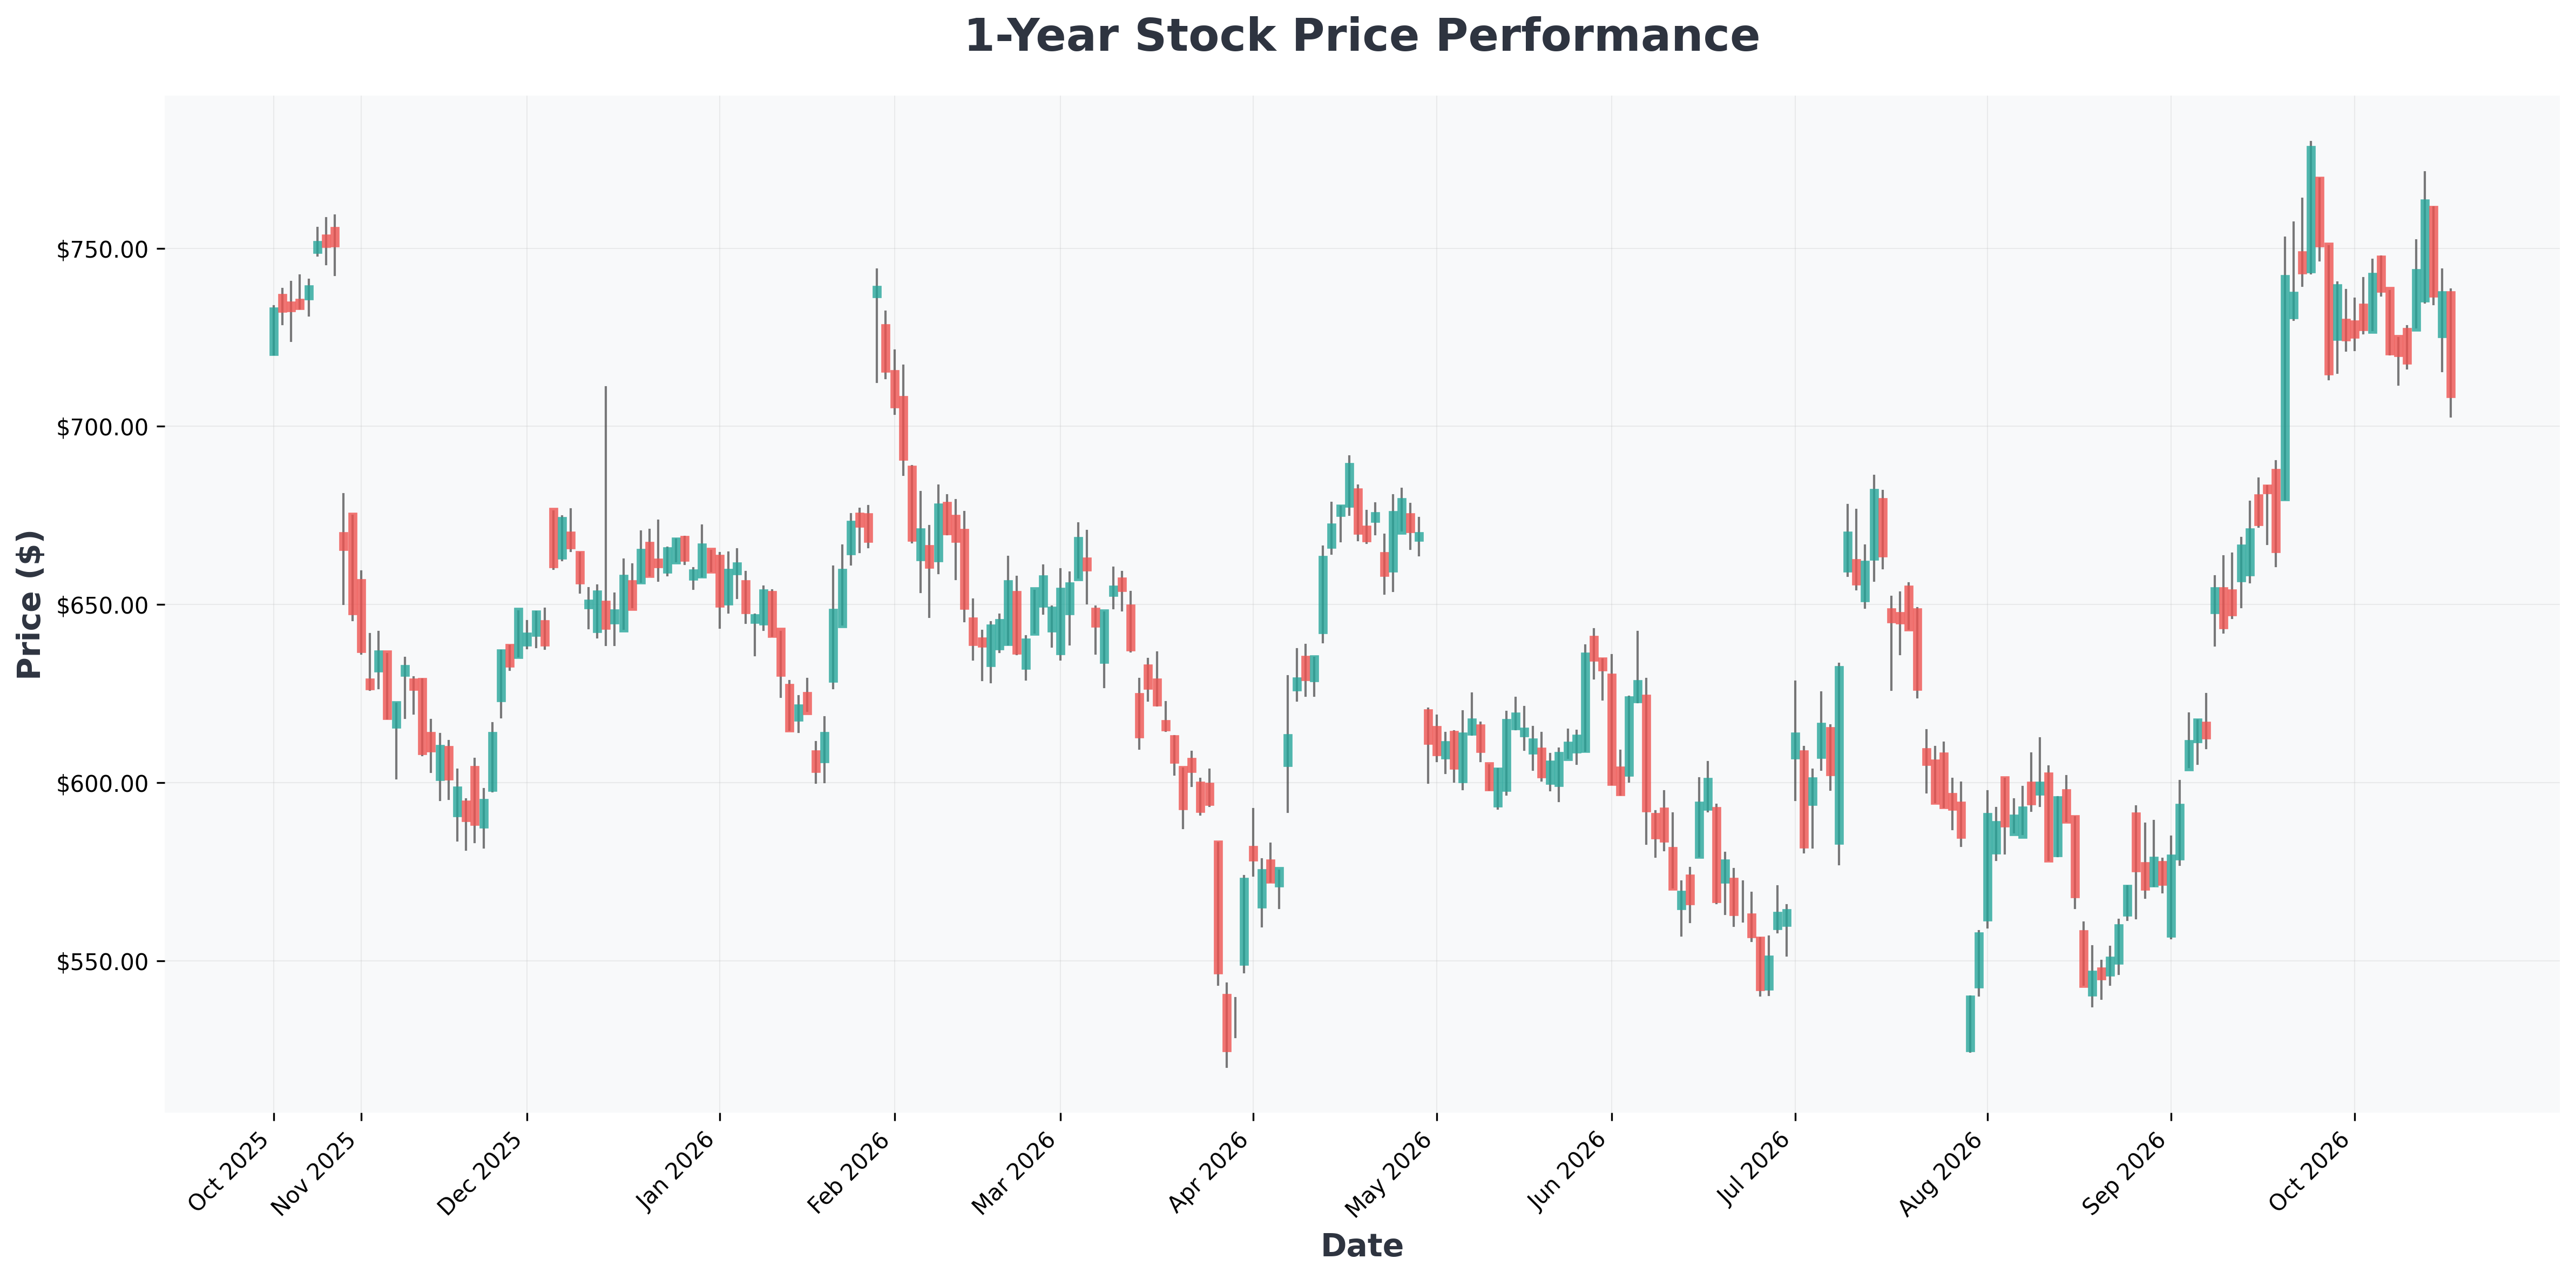
Technical note: NVDA has repeatedly found support near its 50-day moving average during pullbacks over the past year, suggesting institutional accumulation on dips — a pattern worth watching if volatility returns.
This is where the market splits. Growth bulls see a generational entry point, while valuation hawks warn the AI trade is maturing. Here's the debate:

The Valuation Math Behind the Opportunity
Let's put the numbers in perspective. Nvidia's forward P/E of ~23x is remarkable for a company growing revenue at triple-digit rates. Historically, NVDA has traded at a premium to peers — often 35x-40x forward earnings during AI euphoria peaks. Today's multiple sits near the low end of its own five-year range.
| Metric | Nvidia | Magnificent Seven Avg |
|---|---|---|
| Forward P/E | ~23x | ~30x |
| 5-Year Return | +900% | Varies |
| Gross Margin | 74.7% | ~50-70% |
| Market Cap | $5.16T | — |
| Dividend Yield | 0.24% | ~0.5% |
The takeaway: Nvidia is priced like a mature tech company but growing like a startup. That gap is the arbitrage opportunity. 📈
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| AAPL (Apple) | $343 | 39.39 | 46.67 | 148.75% | 32.62% | 16.40% |
| AMZN (Amazon.com,) | $250 | 20.11 | 4.89 | 30.56% | 13.69% | 19.60% |
| GOOG (Alphabet) | $337 | 16.90 | 6.62 | 48.68% | 34.03% | 24.20% |
| GOOGL (Alphabet) | $341 | 17.09 | 6.69 | 48.68% | 34.03% | 24.20% |
| META (Meta) | $709 | 26.73 | 6.92 | 29.85% | 34.83% | 28.00% |
| MSFT (Microsoft) | $529 | 29.47 | 8.88 | 34.04% | 45.11% | 17.70% |
| NVDA (NVIDIA) | $214 | 27.07 | 22.58 | 117.21% | 66.24% | 105.90% |
| TSLA (Tesla,) | $355 | 328.44 | 16.13 | 4.67% | 1.41% | 25.50% |

Scenario Playbook: Bull vs. Bear
Bull Case 🐂
- Agentic AI adoption accelerates, driving CPU + GPU demand simultaneously.
- $20B CPU revenue target is exceeded, adding a fresh growth narrative.
- Forward P/E re-rates toward 30x as earnings visibility improves.
Bear Case 🐻
- AI capex cycle cools as hyperscalers digest prior investments.
- Competitive pressure from custom ASICs (Google TPU, Amazon Trainium) erodes GPU share.
- Multiple compresses further if growth decelerates below 50%.
Bottom Line
Nvidia is not cheap in absolute terms — but relative to its growth rate and its own history, it's arguably the most attractive entry point in years. For investors with a multi-year horizon, the risk/reward skews favorably. Just size positions responsibly: even great companies can correct sharply when sentiment shifts.
