The Federal Reserve left interest rates unchanged at 3.5%-3.75% for the second consecutive meeting, but the unanimous vote of the past is gone. The 9-3 decision on July 29 marks the most significant dissent within the committee in over a decade. 🚨
New Fed Chair Kevin Warsh, who took over in May, has already signaled a stark departure from his predecessor's communication style. He famously requested a "good family fight" — and he got one. With inflation still running hot at 3.5% year-over-year and geopolitical tensions threatening to push energy prices higher, the market is now grappling with a critical question: What happens in September?

The Inflation-Oil Price Tug-of-War 🛢️
The Fed's primary mandate is price stability, and the latest CPI data shows progress — but it's fragile. June's CPI-U reading showed inflation cooled by 0.4% month-over-month, but the annual rate remains well above the 2% target.
The real wildcard is energy. While gasoline and fuel oil prices fell sharply from May to June, that trend has reversed. Crude oil started July around $68.58 per barrel, spiked to $92.19 on July 23, and currently sits just above $84. This resurgence is a direct consequence of escalating Middle East tensions, and it's a risk the Fed cannot ignore.
Investors should note that energy costs have an outsized influence on the headline inflation figure. If oil prices sustain their current levels, we could see a significant bounce in the next CPI report, effectively erasing the progress made in June.
The market is clearly split on this one. Here's how the bulls and bears are positioning themselves:
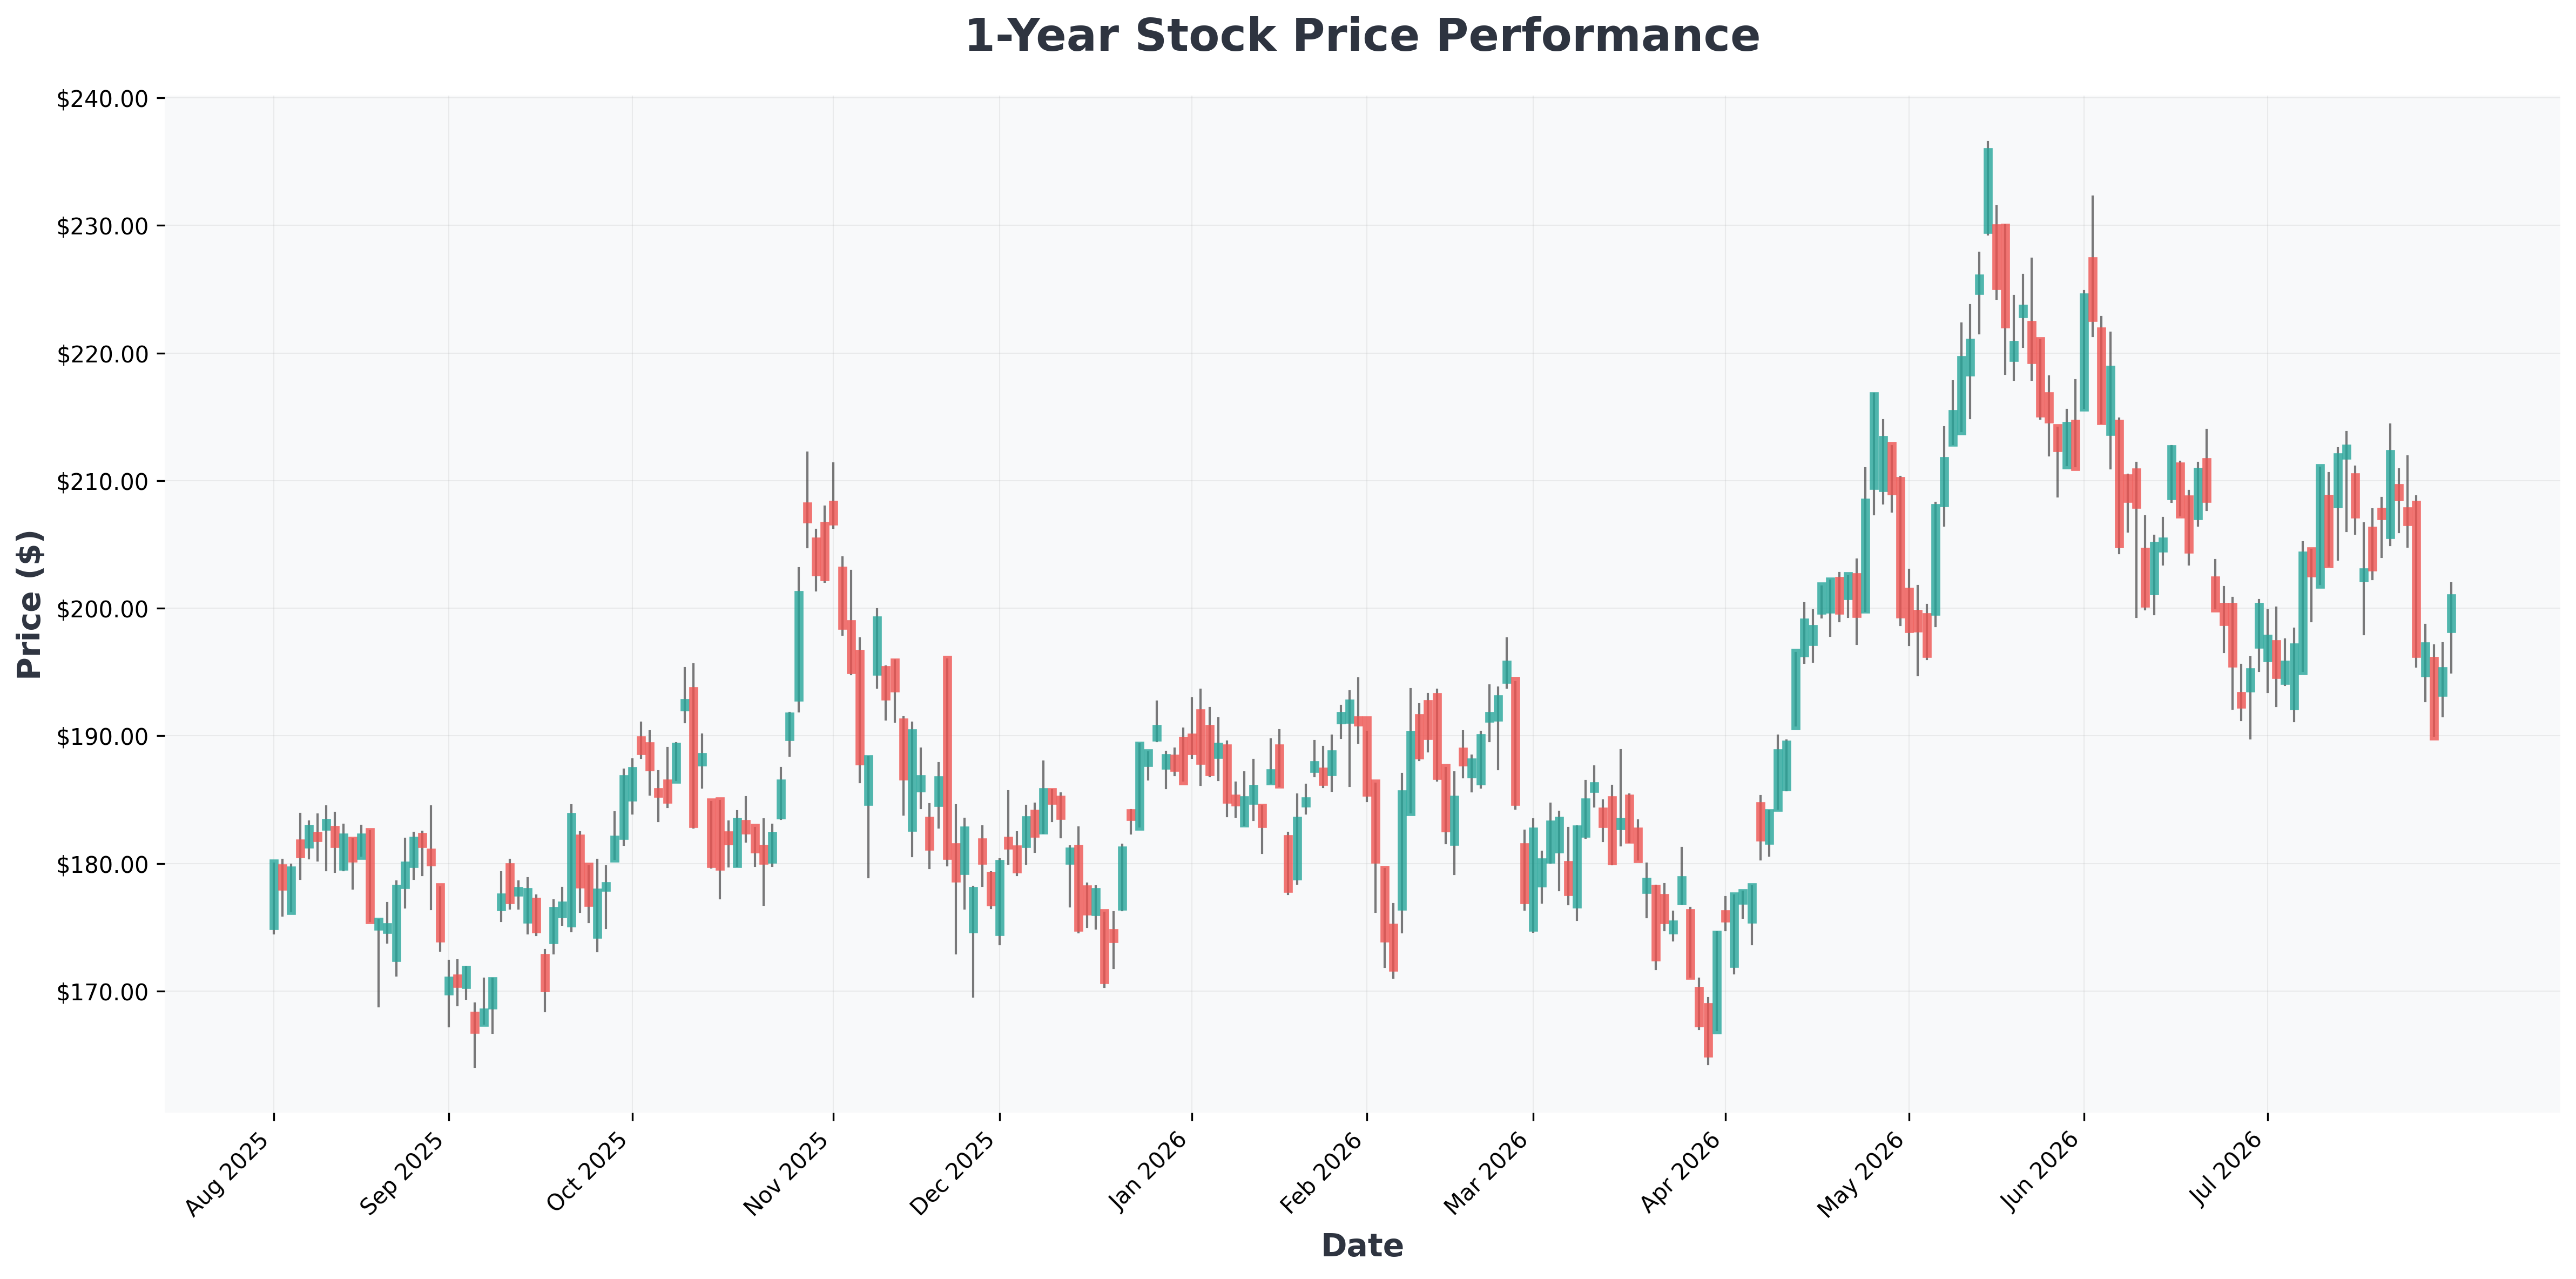

Deciphering Warsh's 'No Forward Guidance' Stance 🎯
Chair Warsh has made it clear he will not offer the kind of forward guidance that markets became accustomed to under Jerome Powell. He stated during his Senate confirmation that he would not "preview" future decisions. This creates a new layer of uncertainty, forcing investors to rely purely on data rather than Fed communication.
Here's what to watch before the September meeting:
| Indicator | Current Status | Potential Impact |
|---|---|---|
| CPI (YoY) | 3.5% | If it rises above 3.7%, a hike becomes more likely. |
| Crude Oil (WTI) | ~$84/barrel | A sustained break above $90 could trigger a policy response. |
| Labor Market | Tight | Strong job gains give the Fed room to hike without political backlash. |
| Dissent Count | 3 Officials | If this grows to 4 or more, the hawkish signal is undeniable. |
Our technical analysis suggests the S&P 500 may find support near 5,400 if a hawkish surprise occurs, but a dovish hold could push it toward new all-time highs. Historically, the market tends to front-run the Fed's actual decision, so expect volatility to spike in late August.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| AAPL (Apple) | $303 | 34.84 | 41.23 | 148.75% | 32.62% | 16.40% |
| GOOG (Alphabet) | $372 | 18.68 | 7.32 | 48.68% | 34.03% | 24.20% |
| GOOGL (Alphabet) | $374 | 18.73 | 7.34 | 48.68% | 34.03% | 24.20% |
| META (Meta) | $590 | 22.22 | 6.15 | 29.85% | 30.88% | 28.00% |
| MSFT (Microsoft) | $488 | 27.18 | 8.19 | 34.04% | 45.11% | 17.70% |
| AMZN (Amazon.com,) | $284 | 22.83 | 6.91 | 30.56% | 13.69% | 19.60% |
| NVDA (NVIDIA) | $207 | 31.69 | 25.61 | 114.29% | 65.60% | 85.20% |
| TSLA (Tesla,) | $322 | 295.49 | 14.38 | 4.67% | 1.41% | 25.50% |

Best & Worst Case Scenarios for September 📊
Best Case (Probability: 35%) – A Dovish Hold
- The Fed acknowledges cooling core inflation and signals that the current rate is restrictive enough.
- Oil prices retreat below $75, easing inflationary pressure.
- Market Impact: A relief rally in equities, particularly in rate-sensitive tech and real estate sectors. The 10-year Treasury yield could fall below 4%.
Worst Case (Probability: 25%) – A Hawkish Hike
- Energy inflation pushes headline CPI above 3.8%, forcing the Fed's hand.
- Warsh brokers a compromise for a 25bp hike, despite dissents.
- Market Impact: A sharp sell-off. The S&P 500 could test the 200-day moving average. The dollar would strengthen, hurting multinational earnings.
Base Case (Probability: 40%) – A Hold with Hawkish Language
- The Fed holds rates but signals that a hike is "on the table" for November.
- Warsh uses the press conference to emphasize the committee's commitment to the 2% target.
- Market Impact: A short-term dip followed by a recovery as investors digest the new normal of higher-for-longer rates.
The Bottom Line: We lean toward a slight increase at the September meeting, as the recent oil price surge is too significant to ignore. Investors should consider hedging against energy-driven inflation with commodities or energy sector exposure.
