📌 The Core Debate: Disposable Tech vs. Financed Infrastructure
Wall Street has a simple bear thesis on CoreWeave (CRWV): GPUs age like consumer electronics, so the company is stuck in a cycle of debt-fueled hardware replacement. But the real-world data from Q2 2026 tells a different story. An Nvidia A100 cluster, an architecture from 2020, just got renewed into 2029. That's nearly a decade of contracted cash flow from a chip most models considered obsolete.
This isn't just a minor data point; it's a fundamental challenge to how the market prices AI compute. If older chips retain economic value, CoreWeave isn't a hardware flipper. It's an infrastructure owner with a hidden asset base.

The Workload Cascade: Why Older Chips Don't Need to Win Benchmarks
The key to understanding CoreWeave's model is that not every AI task needs the latest and greatest processor. The market is splitting by cost and capability:
- Frontier Pre-training: Demands top-tier Blackwell chips where raw speed is critical.
- Fine-tuning & Domain Adaptation: Happens on previous-gen H100s, where customers trade speed for cost efficiency.
- Inference & Everyday Apps: Runs smoothly on older A100s, where reliability and price-per-compute are king.
An older GPU doesn't need to beat a new one on speed. It just needs to be cheap and reliable enough for tasks that don't justify premium pricing. This workload cascading creates a natural aftermarket for every generation of chips, which is exactly what CoreWeave is exploiting.
This is the core disagreement splitting the market right now. Is CoreWeave a genius infrastructure play or a ticking time bomb?

The Real Economics: The Second Lease is the Golden Goose
The financial magic happens after the first contract. Here’s the breakdown:
| Lease Phase | Capital Burden | Revenue Impact |
|---|---|---|
| First Lease (3-5 years) | Recovers substantial hardware cost & debt service | High revenue, but high expense to cover debt |
| Second & Third Leases | Largely recovered capital; only opex remains | High-margin revenue on already-paid-for assets |
This is the zero-cost-basis engine. Once the initial debt is paid down, every dollar from a renewal goes almost straight to the bottom line. It turns CoreWeave from a capital-intensive borrower into a cash-flow-generating asset manager.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| APO (Apollo) | $141 | 50.09 | 4.13 | 11.41% | 21.95% | 63.80% |
| BLK (BlackRock,) | $1,174 | 28.11 | 3.16 | 12.28% | 35.08% | 30.60% |
| BN (Brookfield) | $44 | 81.20 | 2.31 | 2.26% | 25.67% | 8.50% |
| BX (Blackstone) | $144 | 32.27 | 12.77 | 31.37% | 54.36% | 28.60% |
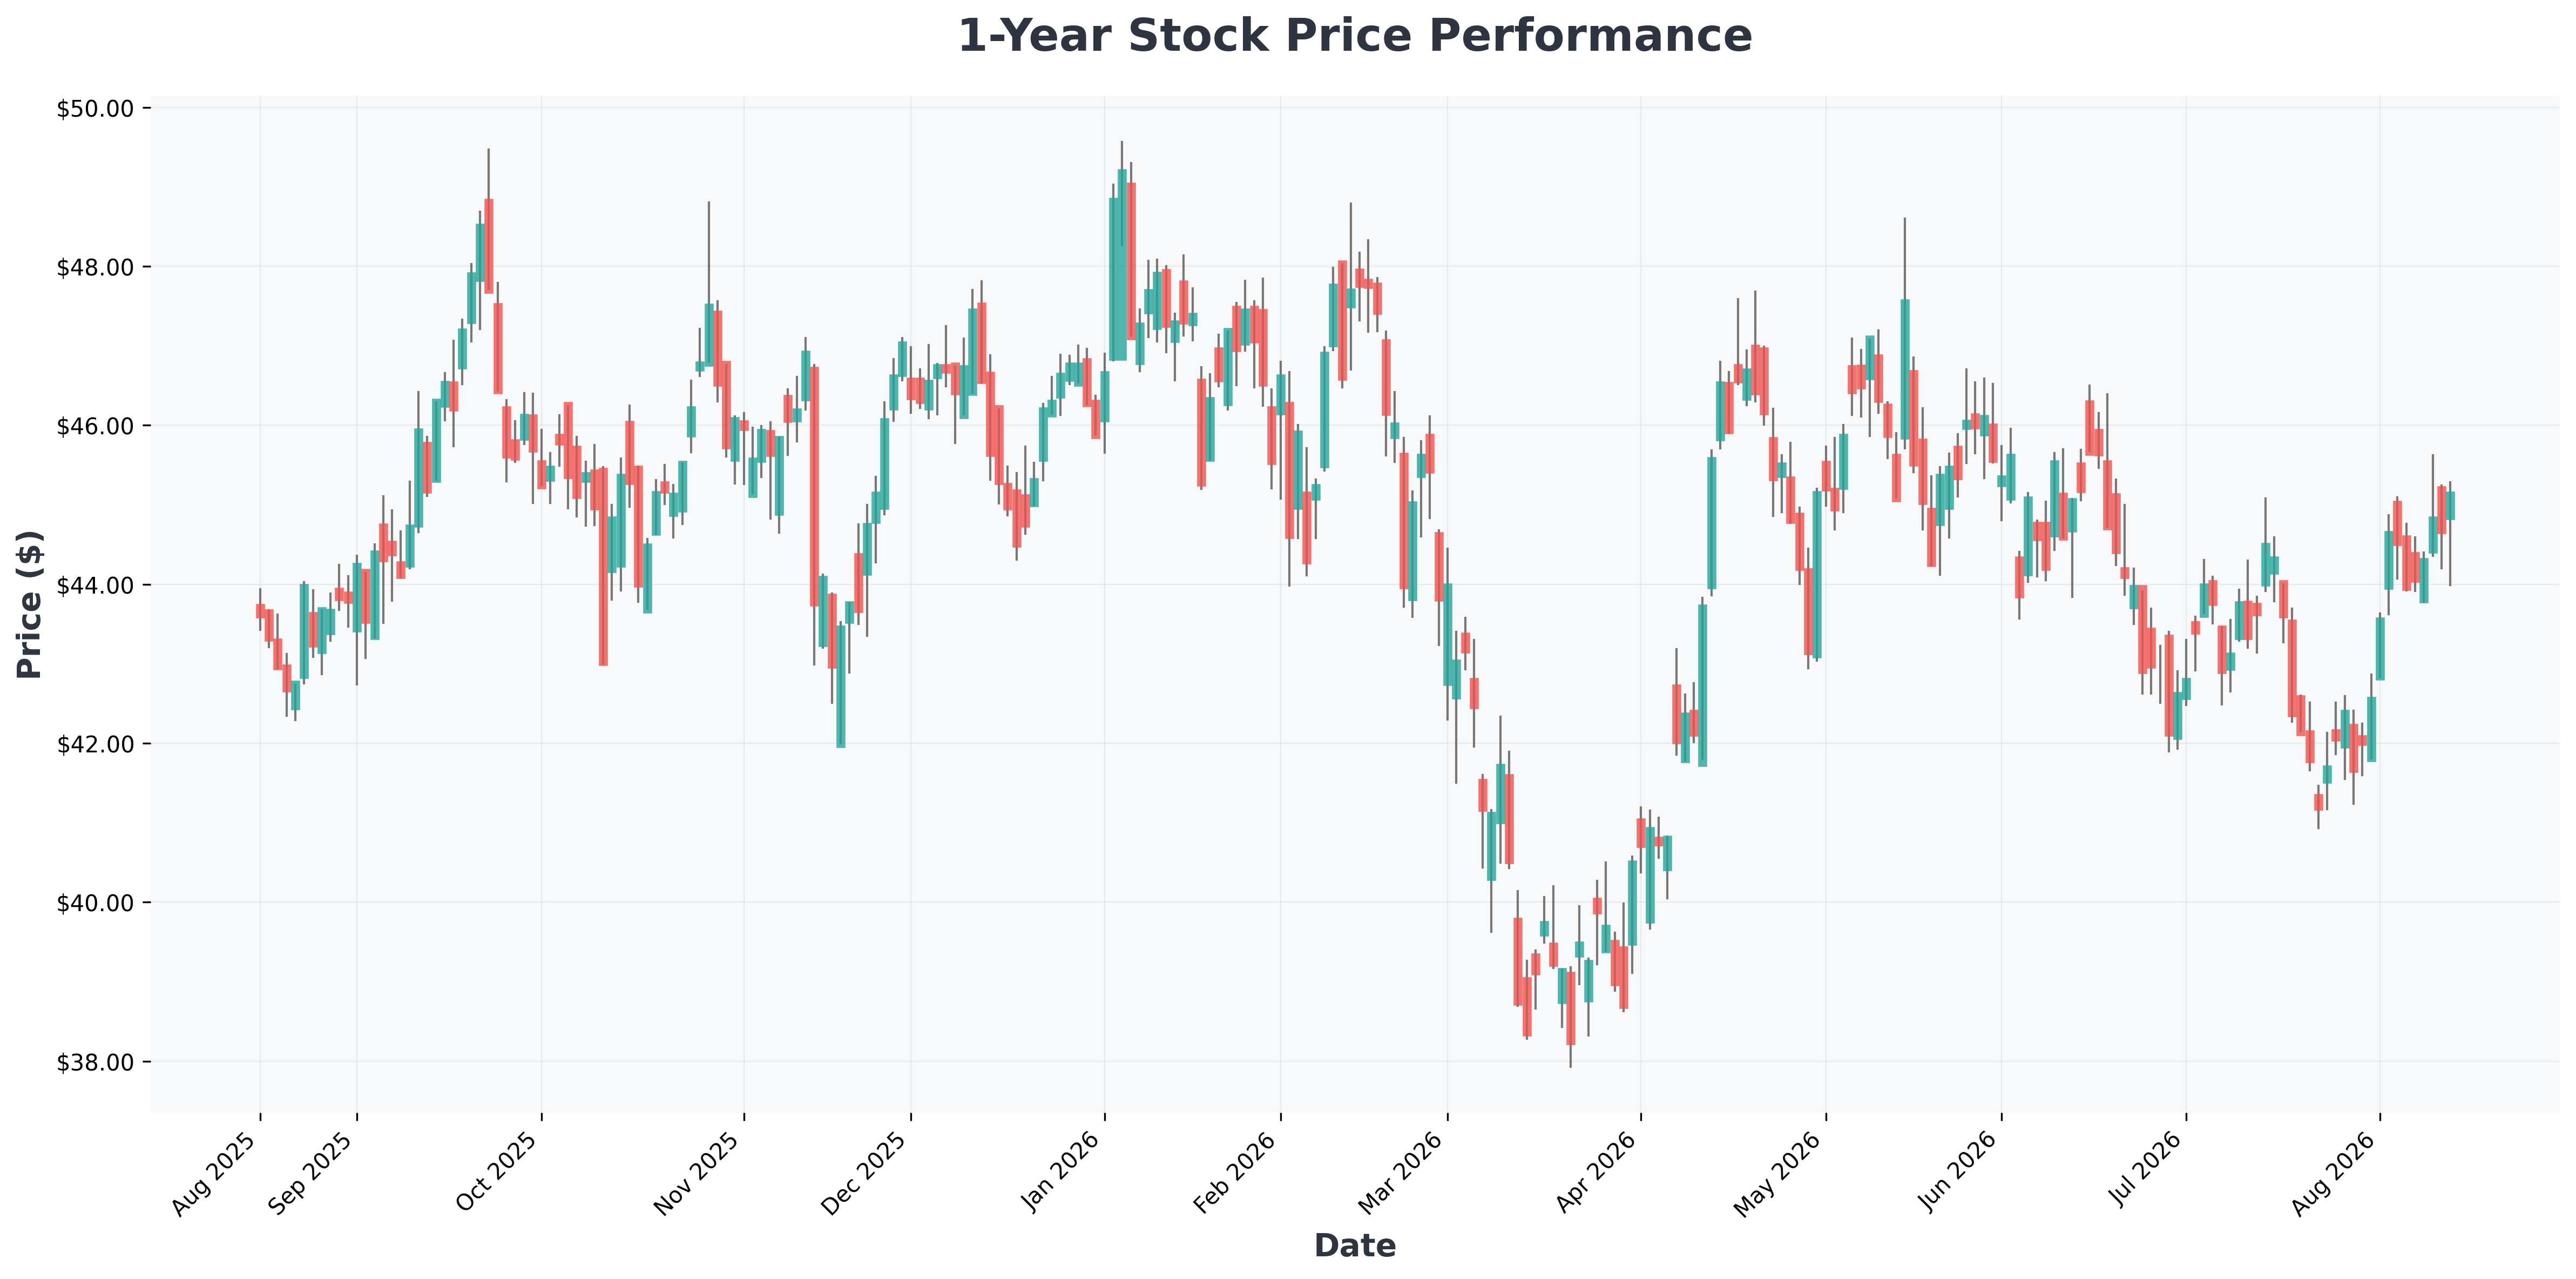
| CRWV (CoreWeave,) | $105 | 0.00 | 11.54 | -43.60% | -1.90% | 112.50% |
| GS (Goldman) | $1,039 | 16.05 | 2.84 | 16.90% | 42.18% | 42.50% |
| KKR (KKR) | $114 | 36.54 | 3.63 | 7.28% | 20.65% | 7.80% |
| NVDA (NVIDIA) | $225 | 34.48 | 27.90 | 114.29% | 65.60% | 85.20% |

The Verdict: A Leveraged Bet on a Flywheel
CoreWeave is a leveraged bet, but it's not a simple one. The A100 renewal proves that residual value exists, and the debt markets are starting to agree. The $2.6 billion DDTL facility, with maturities longer than the backing contracts, shows lenders are now pricing in the value of the second lease.
Best-Case Scenario: If H100 fleets renew at attractive economics and financing costs remain stable, CoreWeave's residual-value thesis strengthens, driving significant margin expansion and de-leveraging over time. The stock would re-rate as an infrastructure play, not just a GPU reseller. 🚀
Worst-Case Scenario: If AI workloads stagnate and rental prices for older chips collapse, the high leverage becomes a death trap. CoreWeave would be forced to sell hardware at a loss or take on more expensive debt, squeezing margins and potentially leading to a liquidity crisis. 📉
The next 12-18 months will be critical. Watch the H100 renewal rates and the cost of new SPV financing. If the flywheel is working, these numbers will be surprisingly strong.