📌 The Big Picture
Cathie Wood just made a massive $362 million statement on CRISPR Therapeutics (CRSP). While the market is fixated on the stock's post-approval drift for Casgevy, Wood’s conviction signal is clear: she’s betting on a second, far more scalable catalyst that most investors are overlooking.
This isn't just a loyalty play to a favorite stock. It’s a calculated pivot toward the future of off-the-shelf cell therapy.

🧬 The Hidden Catalyst: Off-the-Shelf CAR-T
CRISPR Therapeutics isn’t just a one-trick pony with Casgevy. Their real moonshot is in allogeneic (off-the-shelf) CAR-T cell therapy. Unlike patient-specific treatments that take months and cost hundreds of thousands, CRISPR’s approach uses healthy donor cells to target CD19—a protein found on cancerous and autoimmune cells.
Key Pipeline Assets:
- CTX110: Preclinical, targeting blood cancers.
- Zugocabtagene geleucel (formerly CTX112): Phase 1, showing promise in lymphoma and autoimmune diseases like lupus.
This is a paradigm shift. If successful, CRISPR could slash manufacturing costs and democratize access to CAR-T therapies, a market projected to grow at 30% CAGR to $60B by 2034.
The market is split on whether CRISPR's CAR-T pipeline is a game-changer or a distraction. Here’s the debate:

📊 The Market vs. The Narrative
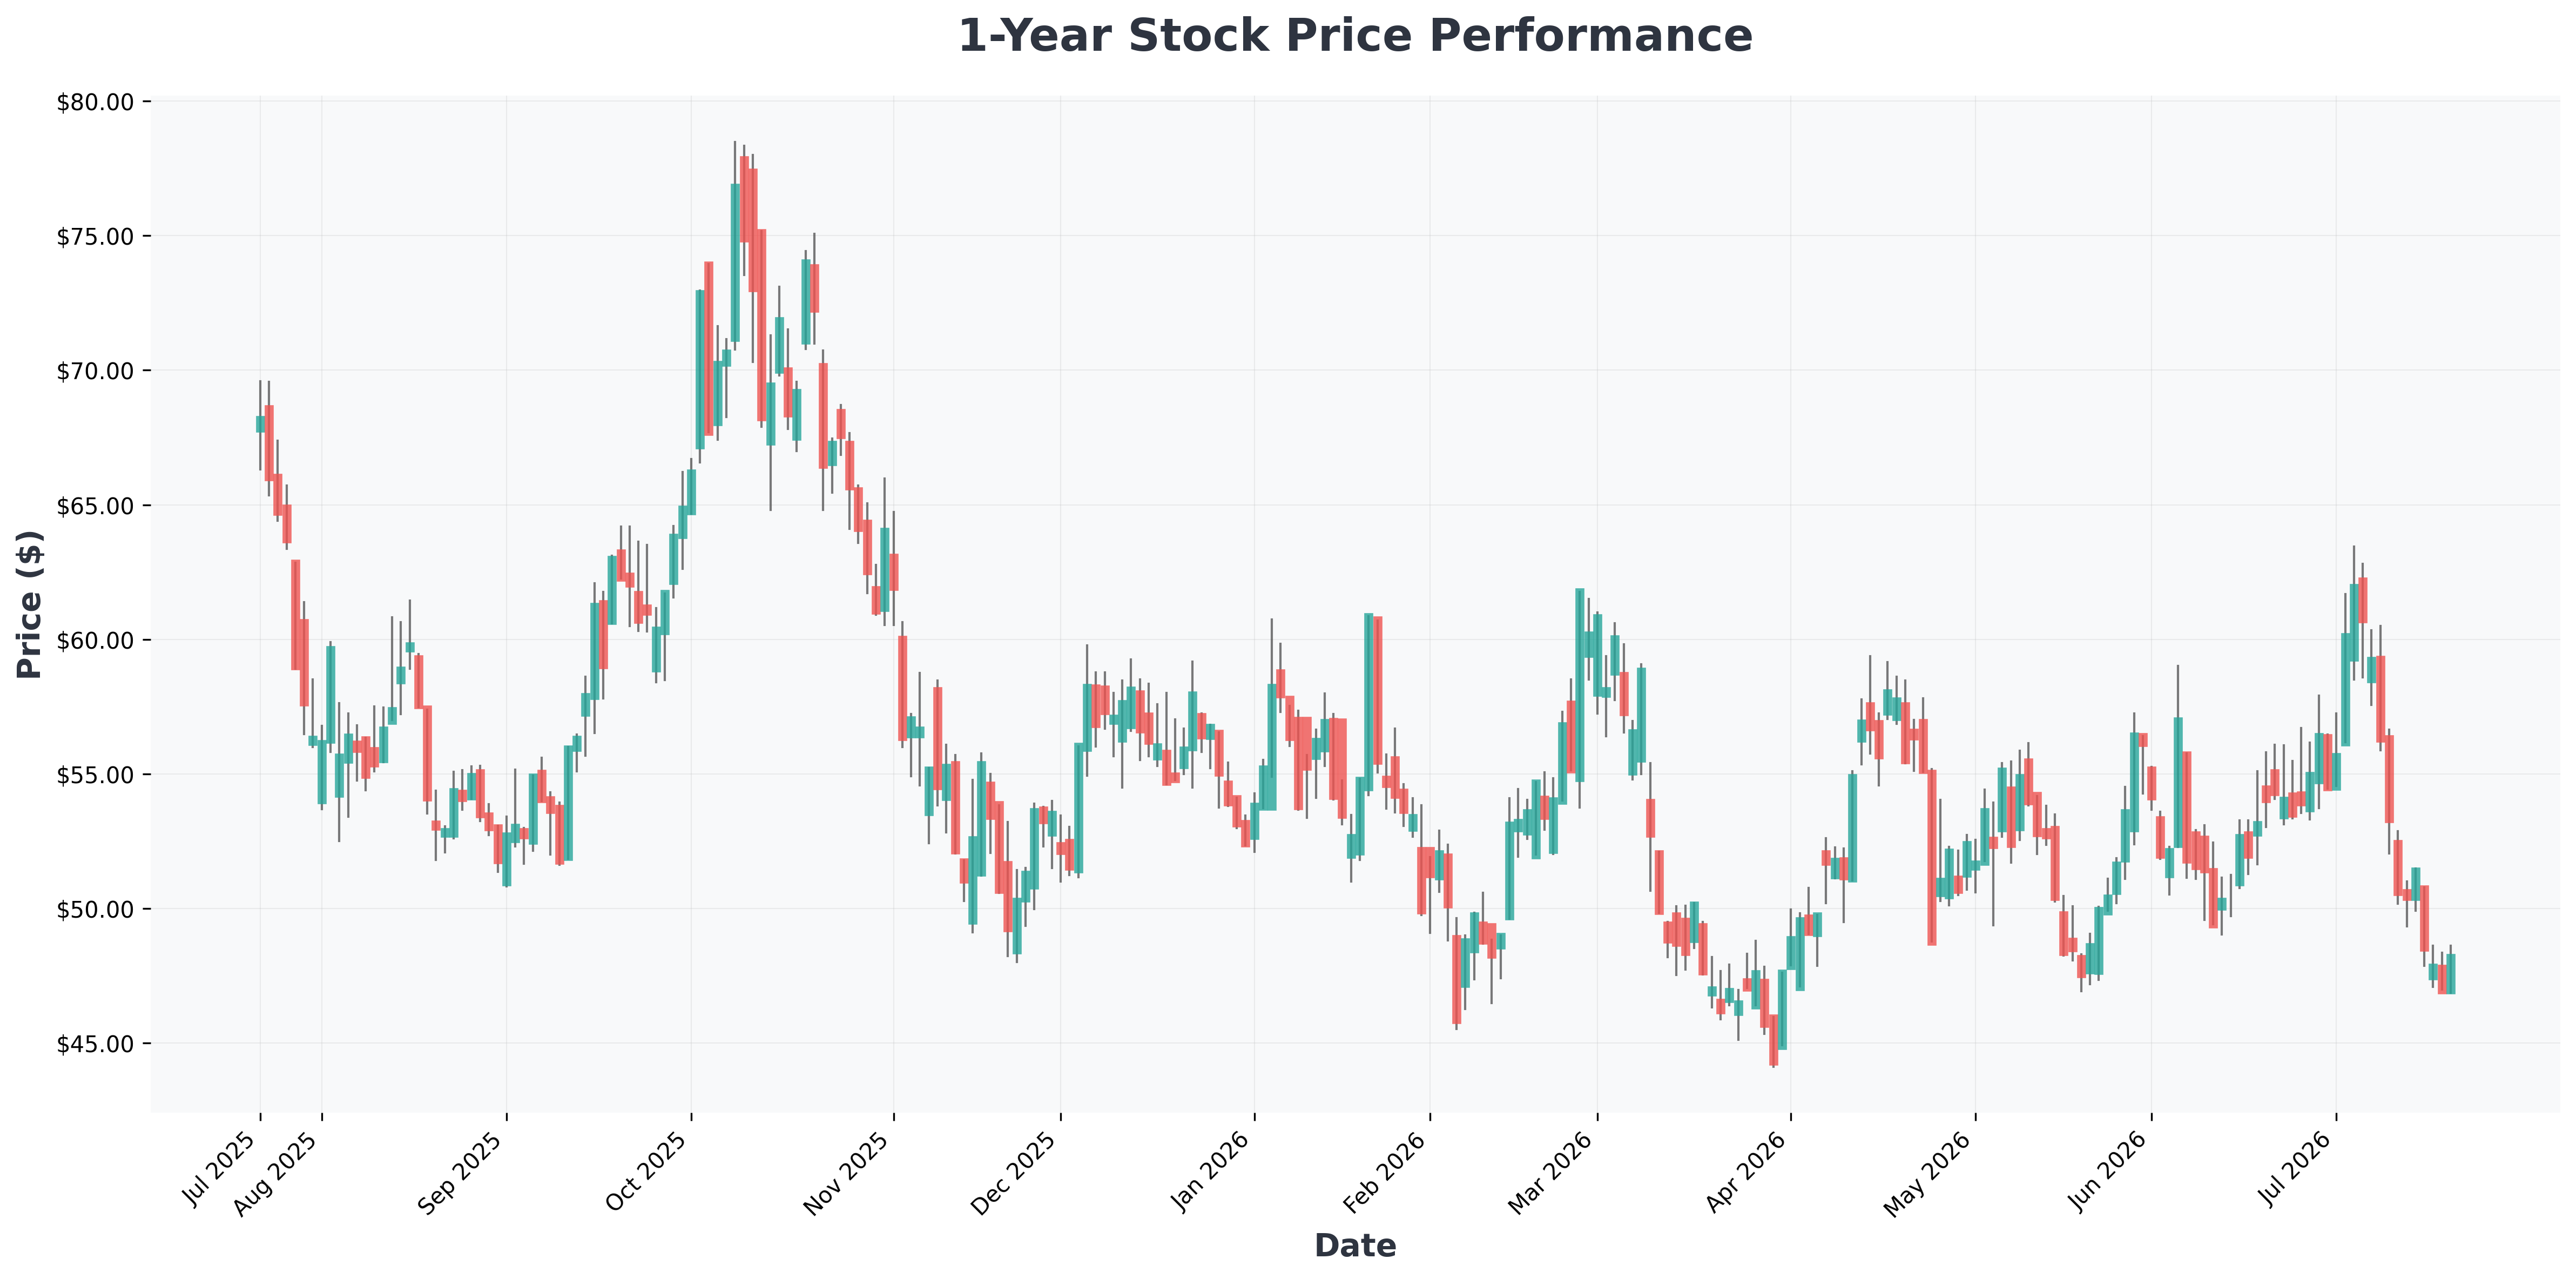
Investors are still pricing CRSP as a single-asset biotech. The technicals tell a different story.
| Metric | Current | Signal |
|---|---|---|
| Price | $47.24 | Near 52-week low of $44.12 |
| Market Cap | $4.6B | Undervalued vs. CAR-T peers |
| ARKK Holding | $270M | Insider conviction at lows |
| 52-Week High | $78.48 | 66% upside potential |
Our Take: The stock is trading near a key support level. A break below $44 could trigger panic, but the risk/reward at these levels favors a patient buyer. The CAR-T data readouts in 2025-2026 are the real needle-movers.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| NVS (Novartis) | $153 | 21.90 | 7.58 | 30.35% | 31.77% | 0.80% |
| GILD (Gilead) | $130 | 17.73 | 6.88 | 43.36% | 39.28% | 4.40% |
| BMY (Bristol-Myers) | $61 | 17.02 | 6.18 | 38.73% | 33.04% | 2.60% |
| CRSP (CRISPR) | $47 | 0.00 | 2.51 | -31.21% | -8933.33% | 68.60% |

🎯 Best & Worst Case Scenarios
Best Case (Bull): CTX112 shows strong efficacy in Phase 2, confirming the off-the-shelf thesis. CRSP becomes a prime M&A target for Big Pharma. Stock re-rates to $80+.
Worst Case (Bear): CAR-T trials fail or are delayed. Cash burn accelerates without a partner. Stock drifts to $30 before a dilutive offering.
Conclusion: Cathie Wood is betting on optionality. The risk is real, but the asymmetric upside in CAR-T makes this a high-conviction portfolio diversifier. Investors should watch the Phase 1 data closely.
