The nuclear energy rally has been one of the most powerful trades of the past year, but it has also created a stark valuation divide. 📌 While investors pile into speculative small modular reactor (SMR) developers and uranium miners, BWX Technologies (NYSE: BWXT) — the company that actually builds the reactors for the US Navy's submarine and aircraft carrier fleet — has been left behind.
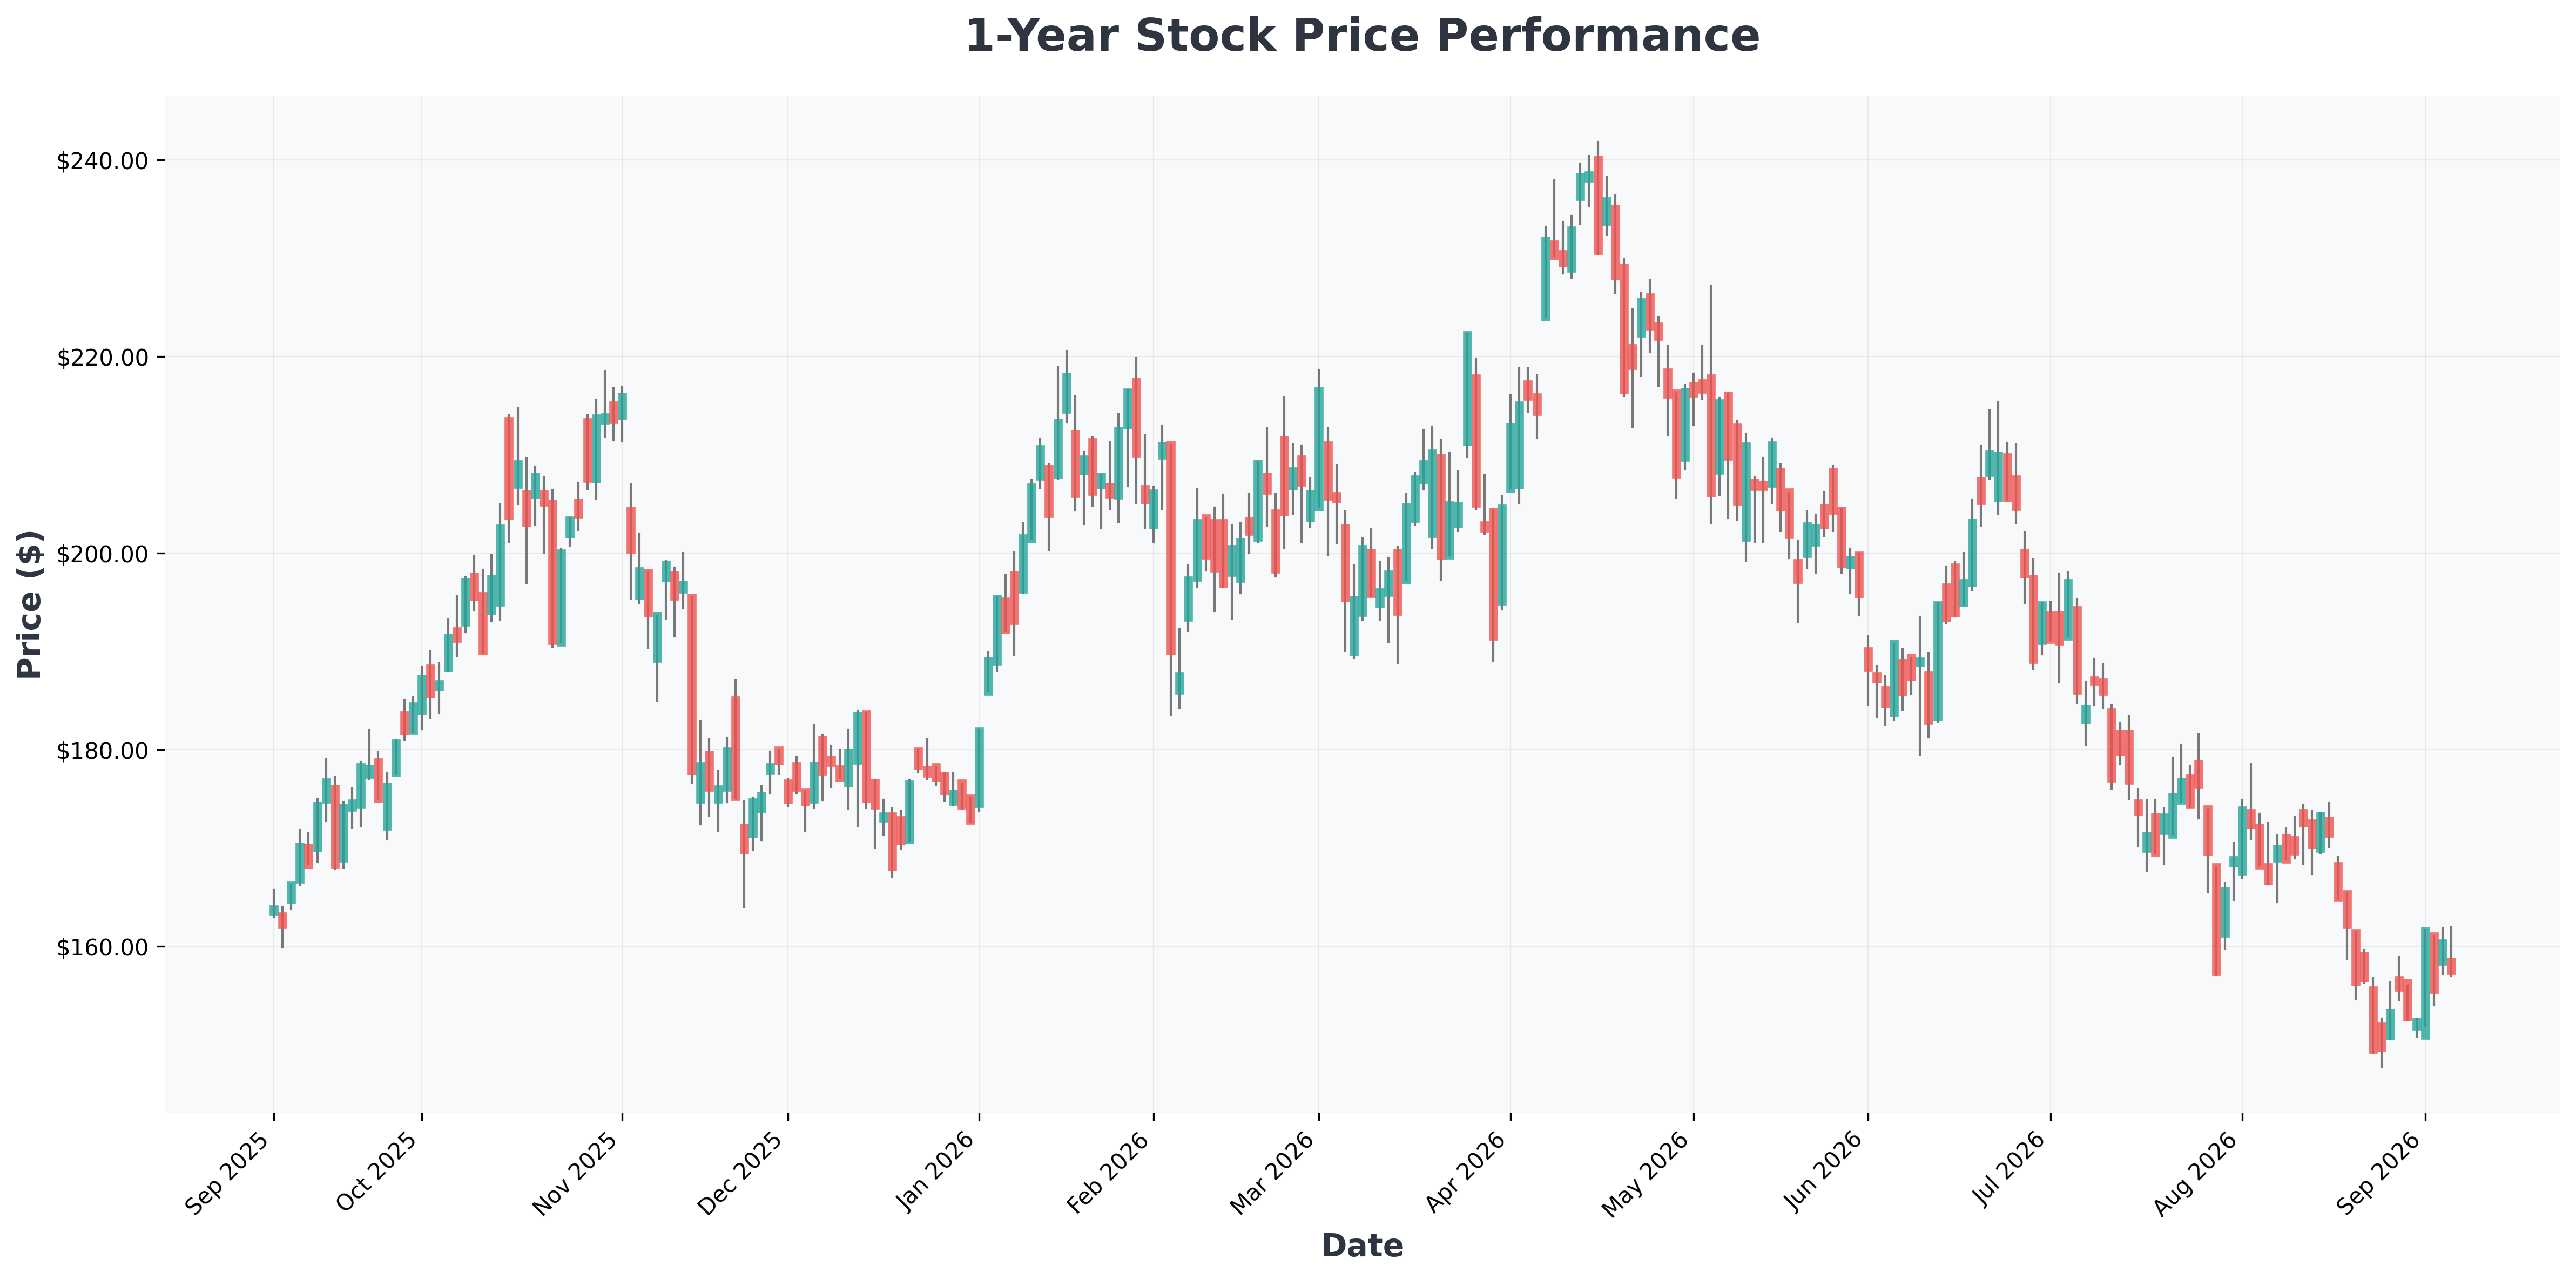
Year-to-date, BWXT stock is down more than 7%, trading at a significant discount to high-flying peers like GE Vernova, NuScale Power, and Oklo. This disconnect between market hype and fundamental value creates a compelling entry point for patient investors.
Let's break down why BWX looks like the most underappreciated name in the nuclear complex right now.

The Numbers: A Monopoly With a Moat 🏰
BWX isn't just another defense contractor. It is the lone manufacturer of nuclear reactors and fuel for the entire US Navy fleet, including Virginia-class and Columbia-class submarines and Ford-class aircraft carriers. This near-sole-source status is backed by layers of regulatory requirements, security clearances, and specialized technology that make it nearly impossible for competitors to enter the market.
Q2 Financial Highlights:
- Revenue: $901.6 million, up 18% year over year
- EPS: $1.07, up 5% from the prior year
- Backlog: Over $8.6 billion, providing multi-year revenue visibility
- New Contracts: $1.4 billion+ with the US Navy, including a $1.3 billion five-year long-lead material procurement deal
This backlog acts as a shield against broader economic downturns. Even in a recession scenario, government defense spending on nuclear propulsion remains a top priority — especially with the recent conflict in Iran highlighting the urgent need for Navy modernization and fleet expansion.
Commercial Expansion: The Hidden Growth Engine 📈
While defense provides stability, BWX's commercial segment is where the upside lies. The company has strategically positioned itself in the next-generation nuclear market:
- Commercial revenue surged 72% to $303 million in Q2
- Adjusted EBITDA jumped 123% to $36 million
- Full-year commercial sales growth forecast: 45%
This growth is fueled by two key acquisitions: Kinectrics (serving SMR and traditional nuclear markets) and Precision Components Group (heavy-walled heat-transfer components). Additionally, BWX produces radioisotopes for diagnostic imaging and targeted cancer therapies — a high-margin healthcare business that diversifies its revenue stream beyond just defense.
This stock has the bulls and bears sharply divided. Let's hear both sides of the argument.

The Valuation Gap: Steal or Trap? 🎯
To understand why BWX is cheap, we need to compare it directly with its nuclear peers. The table below shows trailing P/E, forward P/E, and P/S ratios:
| Metric | BWX Technologies | GE Vernova | NuScale Power | Oklo | Cameco |
|---|---|---|---|---|---|
| Trailing P/E | ~24x | ~80x | N/A (No Profit) | N/A (No Profit) | ~85x |
| Forward P/E | ~22x | ~65x | N/A | N/A | ~60x |
| Price-to-Sales | ~3.8x | ~5.5x | ~450x | ~2,000x | ~12x |
Source: Company filings and public market data.
As you can see, BWX is the only profitable company in this group with a reasonable valuation. It's also growing its top line faster than most of its peers, yet the market rewards the unprofitable dreamers with sky-high multiples.
A contrarian technical note: BWXT stock has found strong support around the $147-$150 level, which aligns with its 52-week low of $147.74. If the stock can hold this zone, we could see a mean-reversion rally toward the 50-day moving average near $170 in the coming weeks. Historically, stocks with this type of fundamental moat and valuation gap tend to close the gap within 6-12 months.
Guidance & Outlook: Confidence From Management 💪
Management raised full-year guidance, signaling strong conviction in the business:
- Revenue guidance: $3.8 billion (up 61.7%)
- Non-GAAP EPS: $4.70 to $4.80 (up 18% at the midpoint)
This is not a company resting on its laurels. It is actively investing in growth while maintaining a pristine balance sheet.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| CCJ (Cameco) | $101 | 173.69 | 8.48 | 5.11% | 9.11% | -7.20% |
| GEV (GE) | $942 | 27.03 | 20.98 | 82.58% | 7.47% | 21.90% |
| CEG (Constellation) | $299 | 29.25 | 3.32 | 15.06% | 8.66% | 23.00% |
| UEC (Uranium) | $12 | 0.00 | 4.01 | -8.96% | -629.66% | 0.00% |
| BWXT (BWX) | $158 | 40.83 | 10.82 | 28.29% | 10.39% | 18.00% |
| DUKU (Duke) | $50 | 0.00 | 0.72 | 9.86% | 27.50% | 1.10% |
| SMR (NuScale) | $10 | 0.00 | 2.64 | -55.18% | -85337.33% | -99.10% |
| OKLO (Oklo) | $41 | 0.00 | 2.33 | -7.70% | -6048.76% | 0.00% |
| DUK (Duke) | $120 | 18.11 | 1.74 | 9.86% | 27.50% | 1.10% |
Best/Worst Case Scenarios 🎭
🟢 Best Case (Bullish Scenario):
- US Navy accelerates submarine production to counter global threats
- Commercial revenue growth exceeds 50% due to SMR contract wins
- Stock re-rates to ~30x forward earnings (still below peers)
- Potential Upside: +35-40% over the next 12 months
🔴 Worst Case (Bearish Scenario):
- Government budget cuts delay Navy procurement
- Commercial acquisitions fail to integrate, dragging margins
- Nuclear industry sentiment cools, compressing all sector multiples
- Potential Downside: -15-20% (but backlog cushions revenue decline)
Final Verdict: Buy the Boring Monopoly 🏦
BWX Technologies offers something rare in today's market: a genuine monopoly with pricing power, a massive visible backlog, and an emerging high-growth commercial business — all at a reasonable valuation. While the market chases the next shiny object, smart money should consider the quiet compounder that's building the backbone of America's nuclear defense.
Investing involves risk, including the possible loss of principal. Please conduct your own research before making any investment decisions. This article represents an opinion and is not financial advice.
