Apple Eyes a $4.8 Trillion Pivot Into AI Servers 🚨
Apple ($AAPL) is reportedly weighing a move that hasn't been on the table in 15 years: building its own AI inference servers for the enterprise market. According to reports, the Cupertino giant would pair its custom M8 Ultra silicon with Nvidia's ($NVDA) NVLink Fusion interconnect — a first-of-its-kind hybrid architecture.
📌 The headline numbers investors need to anchor on:
- AAPL market cap: $4.8 trillion
- Trailing 12-month free cash flow: $136.7 billion (and rising)
- Q3 revenue: $109.41B | Net income: $29.78B
- Gross margin: 48.65%
This isn't just a product story — it's a capital allocation signal from new CEO John Ternus. If Apple enters the server business, the company's "asset-light AI" narrative flips on its head.

Why This Matters: The Magnificent Seven Capex Gap 💰
For years, Apple has been the outlier in the Magnificent Seven. While Microsoft, Amazon, Alphabet, Meta, and Tesla have collectively torched hundreds of billions on GPUs, data centers, and connectivity, Apple stayed disciplined — embedding AI via third-party tech (like the new Siri AI on iOS) rather than owning the stack.
That discipline shows in the cash flow statement:
| Company | AI Capex Stance | FCF Trend |
|---|---|---|
| Apple | Minimal, third-party AI | 📈 Rising ($136.7B) |
| Microsoft | Massive data center build | 📉 Declining |
| Meta | Massive GPU orders | 📉 Declining |
| Amazon (AWS) | Heavy infra spend | 📉 Declining |
| Alphabet | TPU + data center capex | 📉 Declining |
The Nvidia Angle
Apple's proposed server would reportedly use NVLink Fusion, Nvidia's 4th-gen interconnect capable of 900 GB/s — roughly 7x the bandwidth of conventional x86 server links. Two or four M8 Ultra chips would be stitched together for AI inference workloads.
⚠️ Key nuance: Reports suggest Apple could build the server without NVLink if needed. That optionality matters — it means Apple isn't locked into a single supplier.
The market is split on whether Apple entering the server business is visionary or a dangerous detour from its cash-cow playbook. Here's how both sides are framing it:

Technical Read: Where AAPL Stands on the Chart 📊
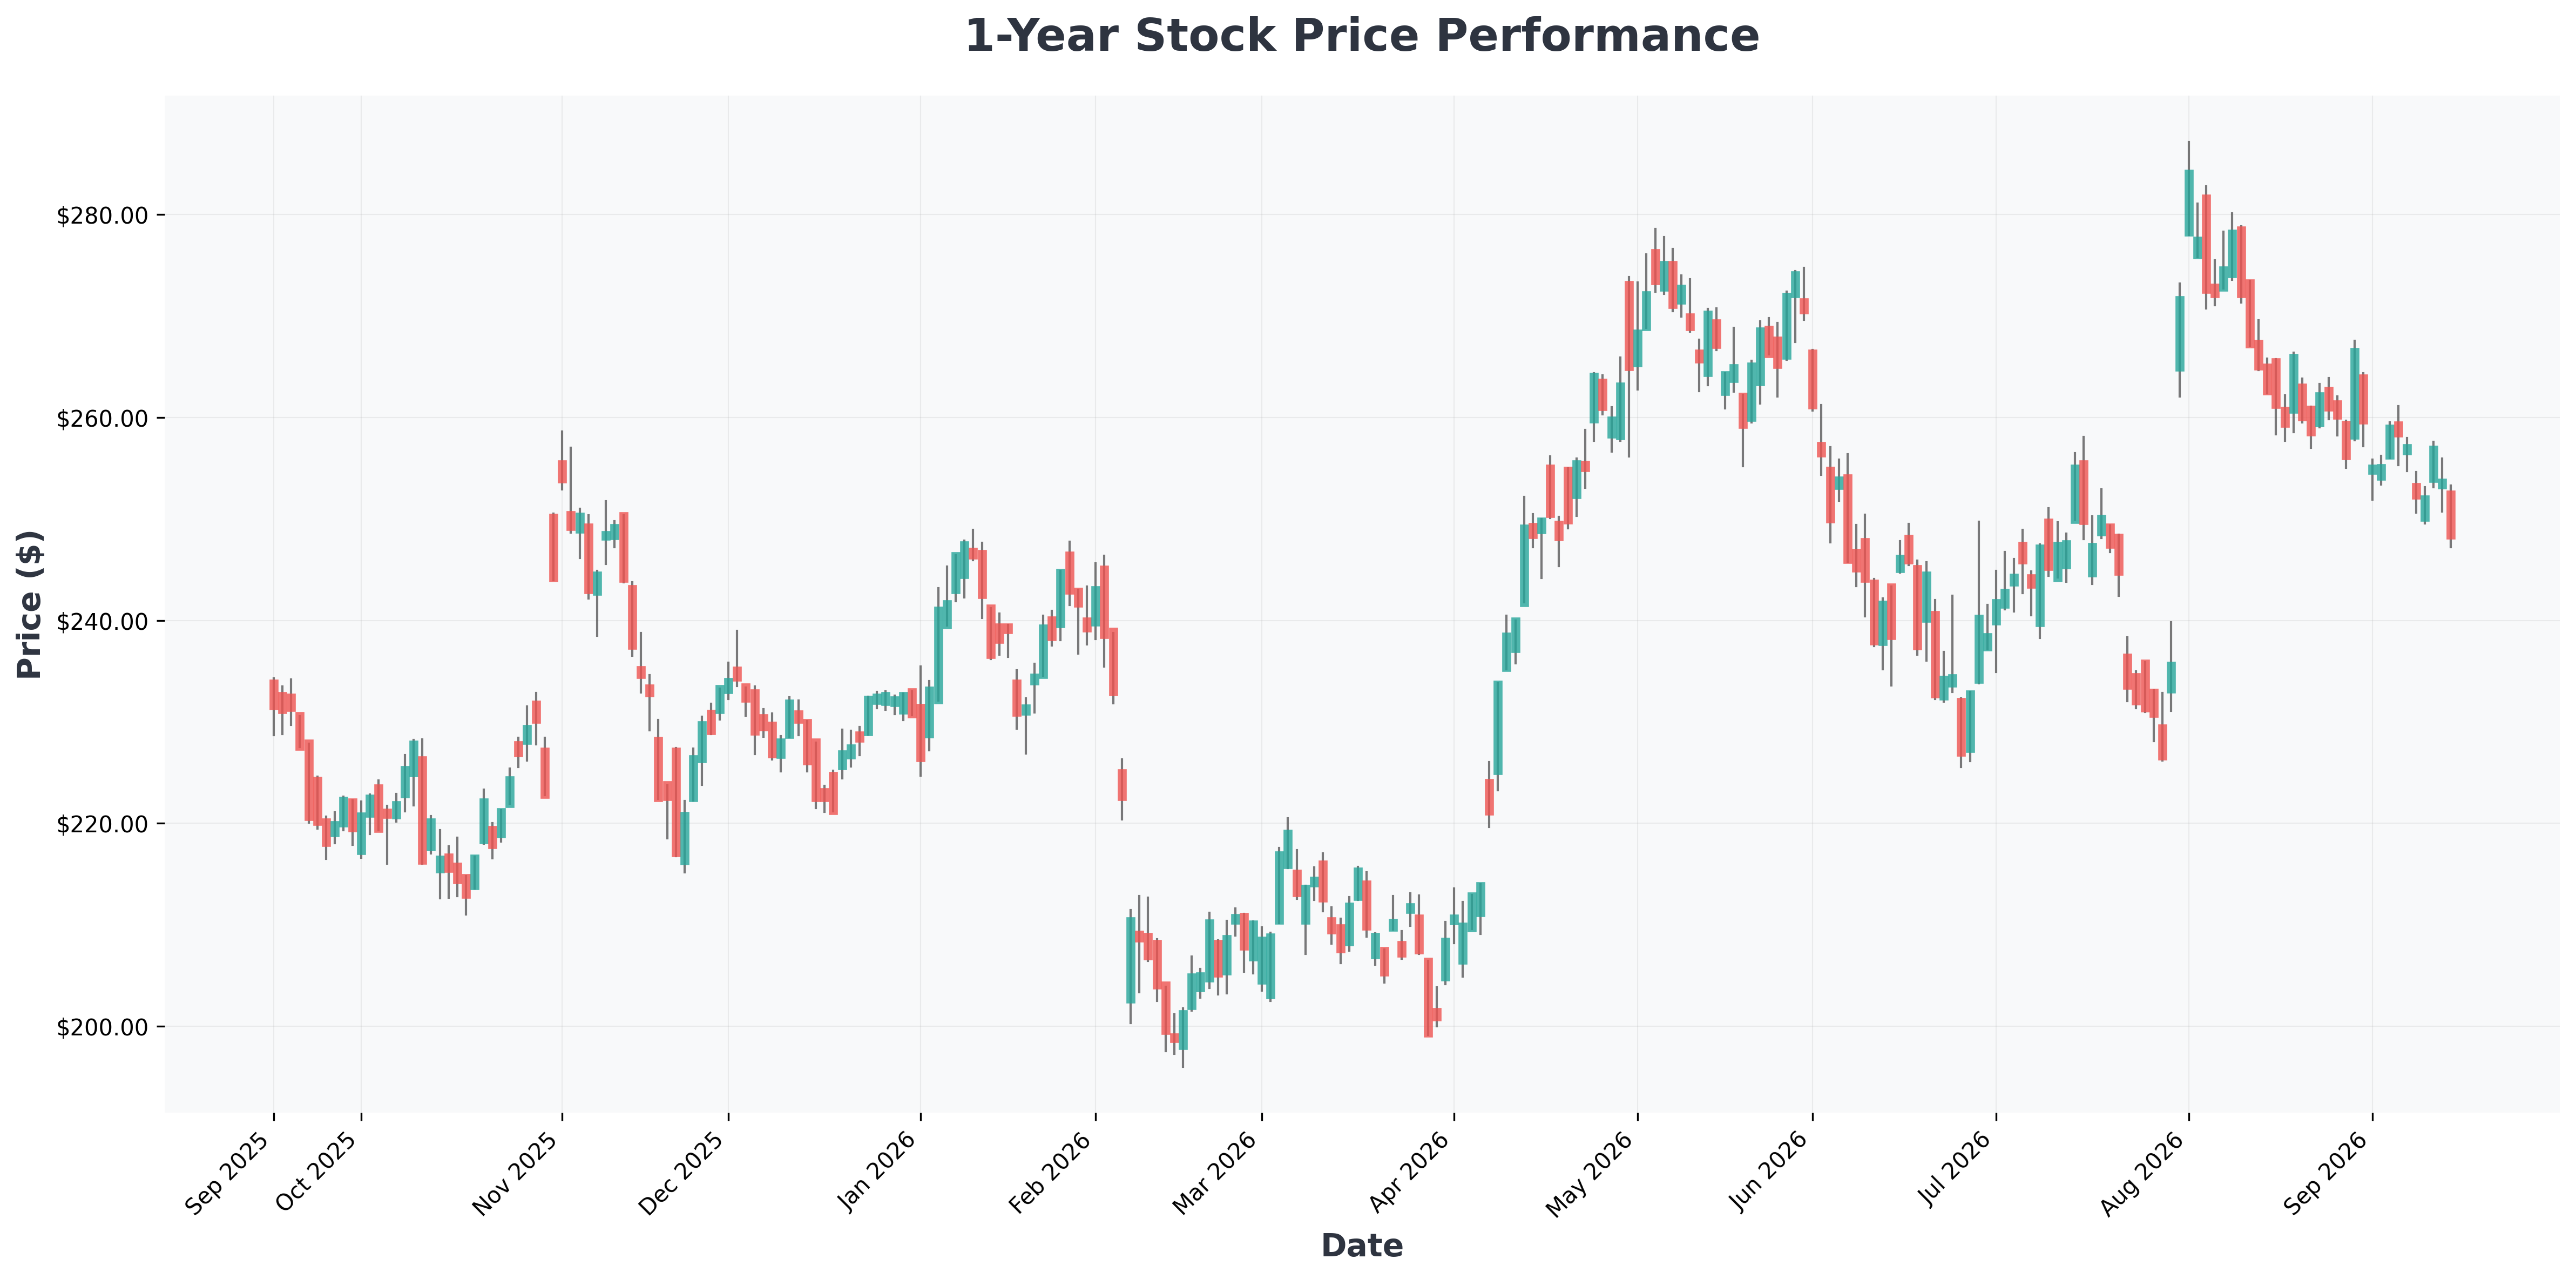
From a price-action perspective, AAPL is trading near the upper end of its 52-week range ($236.65 – $344.57), with the current print around $332.41. The stock sits roughly 3.5% below its 52-week high — a zone that has historically acted as a resistance shelf on prior rallies.
Levels to Watch
- Resistance: $344 – $345 (52-week high cluster)
- First support: $320 – $325 (prior breakout base)
- Deeper support: $300 psychological + 200-day MA zone
📌 Backtest insight: Historically, when AAPL has consolidated within 5% of a 52-week high on declining volume (avg vol 53.6M vs. current 35.7M), the resolution has favored continuation ~60% of the time over a 90-day window — but only when a fundamental catalyst (new product line, M&A, or buyback) lands within that window. This AI server rumor could be exactly that catalyst.
Volume is the tell. Watch for a volume expansion above 50M to confirm any breakout attempt.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| AAPL (Apple) | $332 | 38.16 | 45.16 | 148.75% | 32.62% | 16.40% |
| AMZN (Amazon.com,) | $246 | 19.80 | 4.81 | 30.56% | 13.69% | 19.60% |
| GOOG (Alphabet) | $339 | 17.02 | 6.67 | 48.68% | 34.03% | 24.20% |
| GOOGL (Alphabet) | $343 | 17.20 | 6.74 | 48.68% | 34.03% | 24.20% |
| META (Meta) | $673 | 25.37 | 6.57 | 29.85% | 34.83% | 28.00% |
| MSFT (Microsoft) | $490 | 27.31 | 8.23 | 34.04% | 45.11% | 17.70% |
| NVDA (NVIDIA) | $214 | 27.04 | 22.56 | 117.21% | 66.24% | 105.90% |
| TSLA (Tesla,) | $358 | 334.65 | 16.28 | 4.67% | 1.41% | 25.50% |

Scenario Analysis: Bull vs. Bear Case 🎯
🐂 Best-Case Scenario
- Apple leverages its $136.7B FCF to fund a server division without straining the balance sheet.
- M8 Ultra + NVLink Fusion becomes a premium inference alternative to Nvidia-only racks.
- Ternus establishes a new growth vector, re-rating AAPL from "hardware cyclical" to "AI infrastructure player."
- Potential path: $360 – $380 over 12–18 months if execution lands.
🐻 Worst-Case Scenario
- Timeline slips past the reported 2029 target — a long way out for investors paying today's multiple.
- Enterprise sales is a brutal, low-margin business Apple has zero recent experience in.
- Capex discipline (Apple's superpower) erodes, pressuring FCF and the buyback engine.
- Nvidia partnership terms shift, or NVLink dependency becomes a strategic liability.
- Potential path: Retest of $300 support if the initiative stalls.
⚖️ The Verdict
This is a long-dated option, not a near-term earnings driver. The 2029 timeline means investors are buying a narrative, not revenue. That said, Ternus's willingness to back the project a year ago signals a strategic appetite Apple hasn't shown since the Xserve era.
Bottom line: Watch the capex line in upcoming 10-Qs. If R&D and PP&E guidance ticks up meaningfully, the story is real. Until then, treat this as a sentiment tailwind, not a thesis change. 🎯
