AGNC Investment Just Got a Seat at the Big Kids' Table 📌
AGNC Investment (NASDAQ: AGNC) officially joined the S&P MidCap 400 Index before the opening bell on Sept. 21, part of the index's quarterly rebalancing. The mortgage REIT also picked up membership in the S&P Composite 1500, S&P 900, and S&P 1000.
For a company with a $12 billion market cap and a 14.6% dividend yield, this is more than a vanity badge. Index inclusion forces passive funds — like the Vanguard S&P Mid-Cap 400 ETF — to buy shares, mechanically increasing institutional ownership.
But here's the question income investors actually care about: does any of this protect the dividend? Spoiler — not directly. Let's break it down. 🚨
The Mechanics: Why Index Inclusion Matters
When a stock enters a major benchmark, index-tracking funds are obligated to purchase it. That creates a structural bid under the share price, which in turn makes it easier for AGNC to raise equity capital — a critical lifeline for mortgage REITs.
CEO Peter Federico framed the milestone bluntly: the inclusion reflects "the scale AGNC has attained over our 18-year history" and its role as "a significant source of private capital for the U.S. housing market."
The Real Driver of Dividend Safety
Unlike equity REITs that collect rent, AGNC earns the spread between its return on equity and its cost of capital. On the Q2 earnings call, management pegged current returns in the 15%–17% range — comfortably above the economics needed to support the $0.12 monthly payout.
That spread, not the index membership, is what keeps the dividend alive.
Index inclusion sounds bullish on paper — but seasoned income investors are split on what it actually changes. Here's how the two camps see it:

The Elephant in the Room: Rates and That 20% Drawdown 📉
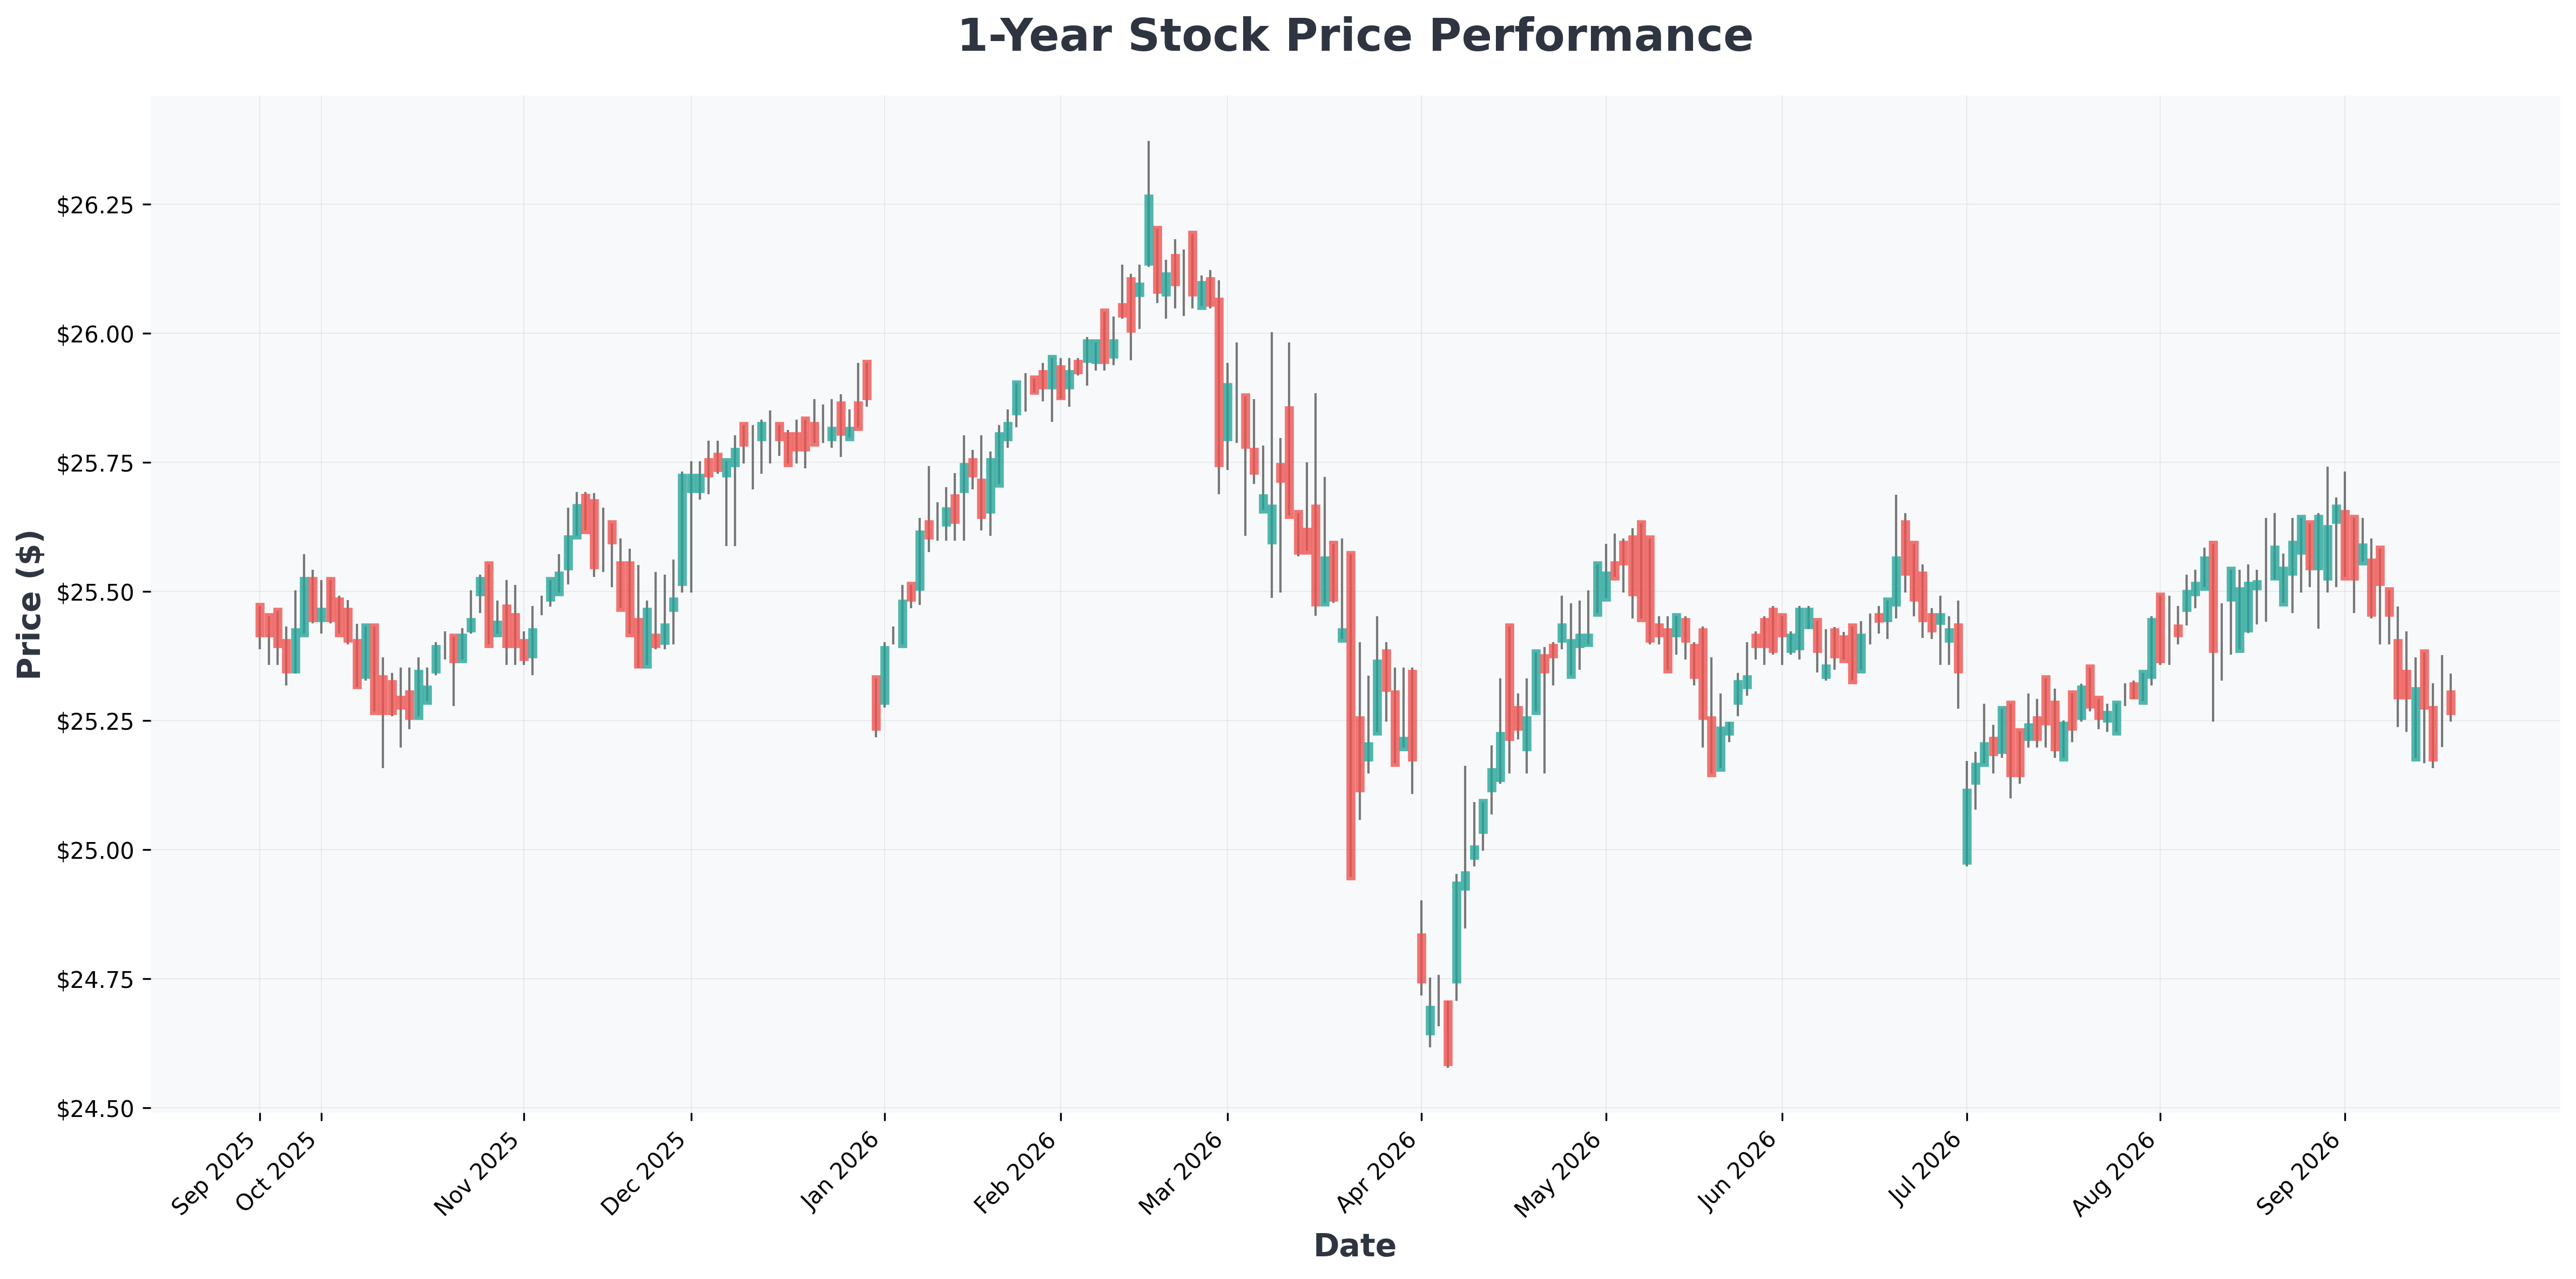
AGNC's stock has slid roughly 20% from its highs earlier this year, which is precisely why the yield has ballooned to 14.6% — the payout itself hasn't changed since April 2020.
The culprit? A punishing rate environment. Renewed inflation pressure pushed the Federal Reserve to hike rates for the first time in three years — and mortgage REITs are extremely rate-sensitive because their book value moves inversely to rate expectations.
Key Numbers at a Glance
| Metric | Value |
|---|---|
| Current Price | $9.97 |
| 52-Week Range | $9.63 – $12.19 |
| Market Cap | ~$12B |
| Monthly Dividend | $0.12/share |
| Dividend Yield | 14.59% |
| Q2 Return on Equity | 15%–17% |
| Avg Volume | 22.1M |
Backtest Insight 🧠
Historically, when AGNC's price-to-book ratio dips below ~0.9x during rate-hike cycles, forward 12-month total returns have tended to compress before recovering — meaning the current dip isn't unprecedented, but patience has historically been rewarded only after the rate cycle peaks.
📊 In-Depth Fundamental Analysis
| Company | Share Price | P/E Ratio | P/B Ratio | ROE | Operating Margin (OPM) | Revenue Growth |
|---|---|---|---|---|---|---|
| AGNC (AGNC) | $10 | 4.96 | 1.10 | 19.80% | 95.61% | 0.00% |
| AGNCL (AGNC) | $25 | 0.00 | 2.79 | 19.80% | 95.61% | 0.00% |
| AGNCM (AGNC) | $25 | 0.00 | 2.79 | 19.80% | 95.61% | 0.00% |
| AGNCN (AGNC) | $26 | 0.00 | 2.84 | 19.80% | 95.61% | 0.00% |
| AGNCO (AGNC) | $26 | 0.00 | 2.83 | 19.80% | 95.61% | 0.00% |
| AGNCP (AGNC) | $25 | 0.00 | 2.79 | 19.80% | 95.61% | 0.00% |
| AGNCZ (AGNC) | $25 | 0.00 | 2.79 | 19.80% | 95.61% | 0.00% |
Scenario Analysis: Where This Goes Next
🐂 Best Case
- Fed signals a pause or pivot; rate volatility cools.
- Index inclusion drives steady passive inflows, lifting the share price toward the $11–$12 range.
- ROE holds above 15%, and the $0.12 monthly dividend stays intact.
- Book value stabilizes, narrowing the discount to NAV.
🐻 Worst Case
- Inflation proves sticky and the Fed hikes again.
- AGNC's book value erodes further, forcing another dividend cut — just as it did in April 2020.
- Passive inflows get overwhelmed by rate-driven selling pressure.
The Bottom Line
Index inclusion is a genuine milestone and a mild tailwind for share price. But it is not a safety net for the dividend. AGNC remains a high-risk income vehicle whose payout lives and dies by the interest-rate cycle. Position size accordingly — and never treat a 14% yield as "free money." 🎯
